I filed stablecoins under “crypto things to get to eventually” for years, which turns out to be exactly the kind of label that hides a spec change. Then I went digging and found the boring part: stablecoin rails reportedly processed over $27 trillion in transactions in 2024, more than Visa and Mastercard combined, per a J.P. Morgan Global Research overview dated September 4, 2025. That figure is secondary-derived, so it gets reported rather than verified status, but even discounted, this stopped being an experiment a while ago. Global market capitalisation passed $300 billion in 2025.
The one-line pitch: all the blockchain perks, near-instant settlement, international reach, 24/7 availability, without the price rollercoaster. These are money rails you can evaluate like a spec sheet, and the spec is mostly excellent with a few honest footnotes. The tradeoffs are real too, and they bite in specific, predictable places.
Key Takeaways
First key takeaway goes here. Keep it to one sentence.
Second key takeaway. One sentence, no bold emphasis.
Third key takeaway. Skip the bullet entirely if not essential.
Key takeaways
- Stablecoins are blockchain tokens pegged to the dollar (or euro, or gold), and the peg mechanism determines the risk you’re carrying.
- Sending $200 from the US to Colombia in stablecoins costs under $0.01 and settles near-instantly. The traditional route: over $12 and several days.
- On-chain settlement is final and uninsured, with no chargebacks, so custody and conversion policies need to exist before volume scales.
What stablecoins are, and why they are not another Bitcoin
Stablecoins are cryptocurrencies pegged to a stable asset, usually the US dollar but sometimes the euro or gold, and that peg is the whole difference from Bitcoin.They run on the same blockchain rails as volatile coins, but where Bitcoin and Ethereum can gain or lose 20% of their value in a single day, a stablecoin is built for steady value. You wouldn’t price a subscription in a coin that gaps overnight.
The purpose follows from the design: blockchain benefits without crypto volatility. The market says people want exactly that.Global stablecoin market capitalisation passed $300 billion in 2025, and 2024 transaction volume came in above $27 trillion, more than Visa and Mastercard combined, per a J.P. Morgan Global Research overview dated September 4, 2025, a secondary-derived figure worth its hedge.
Behavior backs the numbers. During market crashes, Bitcoin holders convert to USDC to preserve portfolio value, a retreat to the save point. And stablecoins handle everyday commerce, treasury movements, and cross-border transfers, which the volatile coins sharing their rails don’t.
How stablecoins hold their peg, four mechanisms, unequal risk
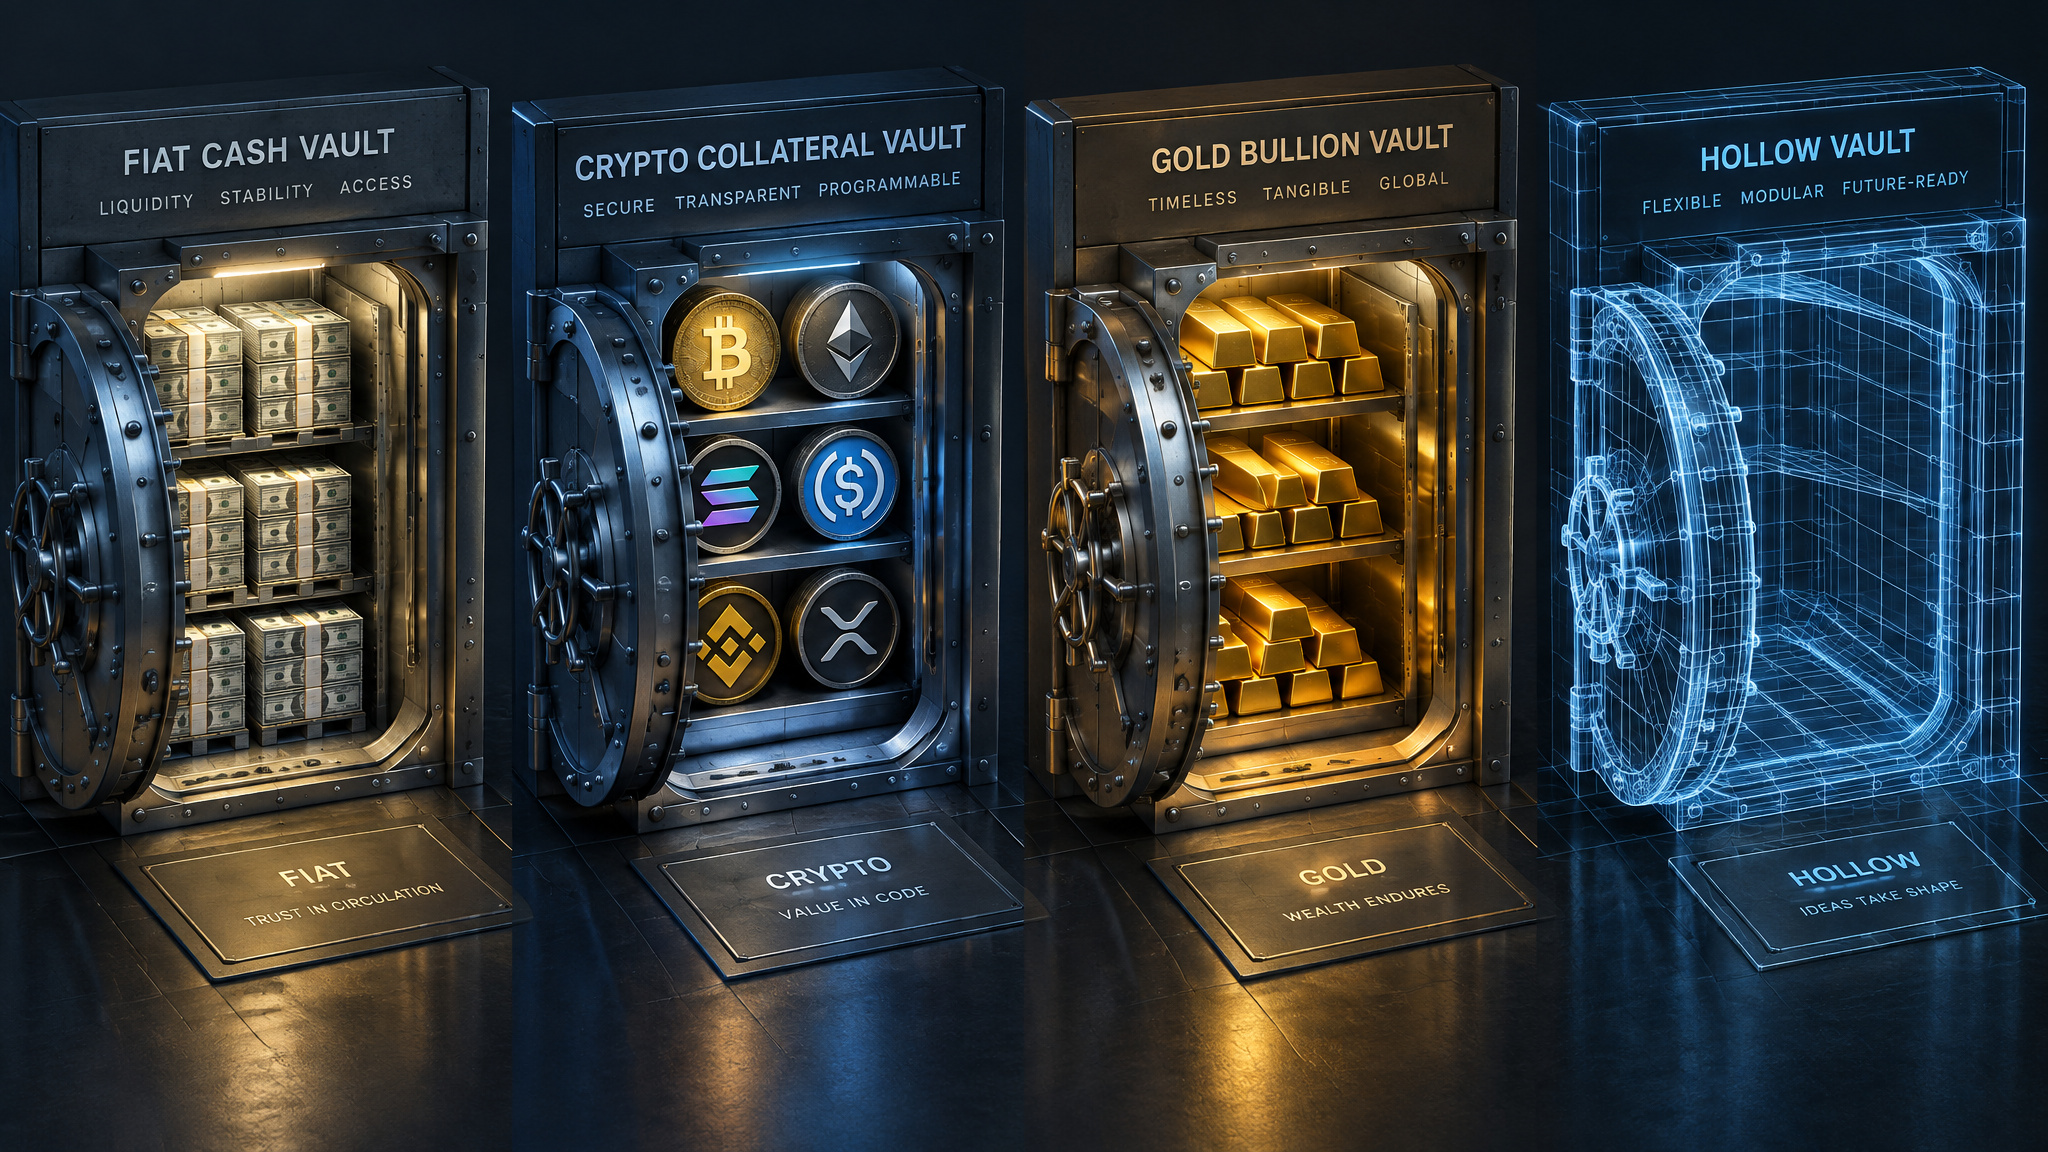
TerraUSD proved how much the peg mechanism matters when the algorithmic design collapsed with no hard collateral behind it. Stablecoins hold their peg through one of four mechanisms, and each answers the same question: what stands behind the promise that one token equals one dollar? Fiat-backed reserves, crypto collateral, commodities, or pure algorithm. The baseline across all four is pegged digital cash, blockchain speed without the volatility, but the designs fail differently, and the failure modes are the part worth reading.
Fiat-backed reserves
Tether (USDT) and USD Coin (USDC) back their tokens 1:1 with cash or cash equivalents, bank deposits and short-term government securities.Redemption for the underlying currency keeps the price steady, provided the reserves are transparent and well-managed. That conditional carries the whole design.
Crypto-collateralised models
DAI, from MakerDAO, takes the recursive route: volatile crypto locked in smart contracts serves as collateral for a stable token. Kind of elegant.The cost of the cleverness is overcollateralisation, often by a wide margin, plus automatic liquidation when collateral values fall sharply. It’s a margin call executed by code, no broker phone call required.
Commodity-backed tokens
Commodity-backed tokens tie value to assets like gold. More stable than plain crypto but still market-exposed, and awkward for everyday pricing and payments.Old money wearing a new interface, with the interface being the only new part.
Algorithmic designs
Algorithmic designs like TerraUSD (UST) adjust supply through smart contracts to hold the peg, an experiment in feedback loops running on money. Proven fragile without hard collateral: the UST collapse is the cited evidence, and it remains the field’s most famous failed build.
What holds across all four: regular audits and clear redemption paths mean a coin holds value more reliably under stress, while doubts about reserve management cause price slippage or worse.Not every issuer publishes audited, real-time reporting, which is why the common newcomer assumption that all stablecoins are interchangeable dollars doesn’t survive its first stress event. Audit cadence and redemption clarity, not the peg label, are the reliability variables. Three questions evaluate any stablecoin: what backs it, can holders redeem, and is reserve reporting audited.
Stablecoins vs traditional bank transfers: the speed and cost math
Stablecoin transfers settle in minutes, cost pennies, become final once confirmed on-chain, and run 24/7 regardless of time zones, weekends, and bank holidays.Bank wires take days through a chain of intermediary banks and clearing systems.
The corridor math makes it concrete: $200 from the United States to Colombia costs under $0.01 via stablecoins and settles near-instantly. The traditional route runs over $12 and takes several days. Scaled down, a $100 bank transfer carries roughly $10+ in fees where sending USDC on Solana costs a few cents, and PayPal and cards skim more per transaction than either. The gap exists because the intermediary-bank chain is gone, and one stablecoin running end to end means no currency conversion fees. That’s what makes microtransactions viable, creator tipping and freelancer payments where fixed fees murder small amounts.
Caveats in the same breath: fees depend on the chain and spike under congestion, and fiat conversion reintroduces currency risk, extra costs, and liquidity- or regulatory-driven delays.
Stablecoins also beat plain USD or a bank account when money needs to move: dollar-pegged tokens transfer globally around the clock, payouts need no local bank account, and they protect purchasing power in high-inflation economies like Venezuela and Zimbabwe. Measured on settlement time, fee, finality, and availability, that’s the comparison stablecoins win.
Cross-border payroll and payouts without local bank accounts
Stablecoins let businesses pay contractors, suppliers, marketplace sellers, and remote employees across countries without maintaining local bank accounts or navigating inconsistent regional banking, which is routing around a bad network path.One digital currency also means less multi-currency juggling and fewer conversion events in the books. The proof case: a US-based company pays a remote employee in the Philippines with USDC, and the payout arrives almost instantly with minimal fees.
The standard cross-border payroll setup looks worse the closer you inspect it. Money moves through correspondent banking relationships, each intermediary adding time and fees, and the composite failure pattern repeats everywhere: the payee asks when the money arrives and the payer can’t answer precisely, because multiple intermediary banks are involved and none of them report back in real time.Stablecoin payroll deletes that entire dependency class, the local accounts, the correspondent relationships, the arrival uncertainty. No named company needed; the pattern is the point.
The remittance side carries weight too. Migrant workers sending money home can skip costly services like Western Union, and the meaningful number is what lands in the family’s pocket versus what the wire service skims off the top.
Access is the quiet unlock. Receiving a payout requires only a digital wallet, and adoption gets easier when counterparties already have one. No branch visit, no onboarding gauntlet, no geographic restriction baked into the banking system.
Faster settlement helps the payer too: employees get earnings sooner, and the business’s cash isn’t stuck in transit.Payroll costs drop, international talent gets easier to attract, and there’s a soft signal value in millennial and Gen Z workers, who tend to seek technologically aware employers, noticing that an employer’s payment plumbing works. The caveat that keeps all of this honest: stablecoin payouts should complement, not replace, traditional methods.
Treasury and cash flow: freeing working capital from transit
The working capital released from multi-day settlement limbo is where the treasury value sits. When settlement takes minutes instead of days, the cash parked in transit shrinks, and money stops sitting idle in the pipeline.Faster settlement also improves cash-flow forecasting, because money that arrives on schedule is money you can plan around. Time-to-clear is the metric that matters here, and it’s the one traditional rails can’t compress.
Freed working capital enables just-in-time payments, quicker reinvestment, and smarter capital allocation. Less dead inventory in the money pipeline.
There’s an FX dividend too: one pegged unit means less currency conversion and less FX exposure quietly eating margin, and predictability lets companies fold stablecoins into pricing, accounting, and workflows without hedging gymnastics or constant revaluation.
Programmability: what banking rails simply cannot do
Smart contracts make stablecoins programmable: automated escrow, conditional payouts tied to specific events, recurring transactions, and instant revenue splits. Speed and cost improve payments you already make; programmability enables payments banking rails can’t express at all. Money that executes logic.Instant revenue splits alone justify the category: a sale divides between collaborators the moment it clears, no invoice cycle.
The fiat-to-DeFi path runs through the same tokens. Deposit fiat with an issuer, receive stablecoins, then trade, lend, or borrow on-chain, for example parking DAI with a DeFi protocol that pays interest or accepts liquidity provision. No yield promises here, just the plumbing.
One precision correction: transactions are pseudonymous, not anonymous. Useful for financial privacy, but everything sits on a public ledger.
And the caveat stays glued to the capability: implementation requires technical expertise. Programmability is a capability, not a turnkey feature.
Financial inclusion and inflation protection: who benefits most
Dollar-pegged stablecoins protect savings from inflation: the holder gets the dollar’s stability, so local devaluation stops eating purchasing power. In Venezuela and Zimbabwe, citizens use them as de facto dollar access amid hyperinflation, a people problem addressed by a mechanism rather than a feature bullet.
The hardware requirement is a smartphone and an internet connection. No bank account, no geographic restrictions, low entry barriers for the unbanked and underbanked, and regions with thin banking infrastructure are exactly where this matters most.
The protection only holds if the token holds its peg, which ties straight back to issuer trust and redemption reliability from the peg mechanisms above.And adoption still runs into digital literacy, internet reliability, wallet security, and AML and tax compliance. The mechanism is plain; the friction is real.
Merchants, transparency, and the security tradeoff
The checkout benefits and the security tradeoff arrive in the same package.
Merchant adoption at checkout
Merchants accepting USDT or USDC gain lower fees and faster settlement, and blockchain settlement is final by design: the same finality that eliminates chargeback fraud against merchants eliminates error recovery for consumers.Some e-commerce platforms reported cutting payment costs by 65% after adopting stablecoin systems, a promotional claim with no named source behind it, so take it as directional at best.
On-chain transparency and security
Immutable on-chain records and public audit trails enable instant auditability, continuous monitoring, and faster irregularity detection, versus the opacity of transfers routed through multiple banks. Cryptographic protocols reduce fraud and unauthorized access, though security varies by platform consensus mechanism.
The honest constraints: what stablecoins don’t do
Stablecoins don’t do reversibility, insurance, or chargebacks: transfers are final by design, tokens are not insured, and there’s no dispute mechanism, so a mistyped address or compromised keys typically means the money is gone. Most ERP, accounting, and treasury software predates blockchain transactions, which creates reconciliation and audit overhead from day one.
Irreversible transfers, no insurance or chargebacks
Irreversibility is design, not defect. No central insurer, no dispute process, no recourse when things go wrong. Responsible adoption needs strong policies, secure infrastructure, internal controls, and custody or private-key management.
Regulatory fragmentation
Rules differ widely by region, and jurisdictions worldwide have yet to finish writing their stablecoin rules.KYC (Know Your Customer), AML (Anti-Money Laundering), licensing, and reporting requirements stack with no consistent global playbook, GDPR-style data handling still requires care, and AML and tax compliance still apply.
Back-office and integration reality
The boring back-office constraint, not regulation, is the real adoption barrier. Legacy ERP (enterprise resource planning) and treasury systems predate blockchains, partner and vendor adoption varies widely, and integration friction is a typical setup gap rather than a solved problem.
On the investment question, the verdict is no. Stablecoins are a utility product for payments and holding value, not an investment.They fit businesses and people moving money, not yield seekers. Peg risk, no insurance or chargebacks, and issuer trust are the honest reasons why.
The infrastructure that makes stablecoins usable at scale
Three layers make stablecoins practical at scale: cross-chain bridges, enterprise custody, and finance tooling that already exists. Bridges move tokens between blockchains by locking them on one network and recreating them on another, and multi-network support lets companies pick a chain by speed, cost, and function. Enterprise-grade wallets let finance teams store and move stablecoins without managing private keys. The proof it plugs into familiar tooling: Stripe supports holding stablecoin balances globally and accepting them at checkout with automatic conversion or fiat settlement, across 125+ payment methods, 195 countries, 135+ currencies, and 99.999% historical uptime, while Rapyd Disburse runs bank transfers, RTP networks, instant card payouts, e-wallets, and stablecoins across 190+ countries and 120+ currencies with built-in FX and multi-currency accounts. Vendor figures date to mid-2025.
For anyone learning how to buy stablecoin, the starting point is understanding what backs the token and how its peg works. That gives you a basis for choosing which stablecoin to use before working it into a payment workflow.
Where stablecoins add value: a decision framework
Starting with stablecoins as a small business works best as a side project: name the payment problem, run one pilot, write the config before you scale.
Step one is diagnosis.Identify the actual pain, whether slow cross-border transfers, steep fees, patchwork banking access, or cash idling in transit, then estimate the recoverable time, cost, or idle capital. If the number is small, you’ve saved yourself a weekend.
Step two is the pilot. Run a focused test on one payout stream or cross-border workflow before broader adoption.Adoption gets easier when counterparties already use digital wallets.
Step three is policy, decided upfront: which stablecoins to use, how they’re stored and custodied, acceptable exposure, and when to convert back to fiat. Clear policies reduce risk as volume grows. Start small, measure, expand.
Frequently Asked Questions
What is the definition of a stablecoin?
A stablecoin is a cryptocurrency pegged to a stable asset, usually the US dollar but sometimes the euro or gold. It runs on the same blockchain rails as volatile coins, but it’s designed to hold steady value instead of swinging 20% in a day. The peg is the whole point: blockchain speed without crypto volatility.
What is the difference between a stablecoin and cryptocurrency?
Stablecoins are technically cryptocurrencies, but they’re built for steady value while Bitcoin and Ethereum are built for price appreciation. Bitcoin can gain or lose 20% of its value in a single day; a stablecoin targets one token equals one dollar. That’s why you’d pay a subscription or a contractor in a stablecoin but not in Bitcoin.
Why would anyone want stablecoins?
Because they combine blockchain perks with stable value: near-instant settlement, 24/7 availability, international reach, and pennies in fees. Sending $200 from the US to Colombia costs under $0.01 and settles near-instantly, versus over $12 and several days through traditional rails. They also give people in high-inflation economies like Venezuela and Zimbabwe de facto dollar access.
How do stablecoins hold their peg?
Through one of four mechanisms: fiat-backed reserves, crypto collateral, commodities, or pure algorithm. Fiat-backed issuers redeem tokens for the underlying currency, which keeps the price steady provided reserves are transparent and well-managed. Crypto-collateralised models like DAI overcollateralise and liquidate automatically when collateral values fall. Algorithmic designs adjust supply through smart contracts, and TerraUSD’s collapse showed how fragile that is without hard collateral.
Why use stablecoins instead of USD or a regular bank account?
When money needs to move, stablecoins win on settlement time, fee, finality, and availability. Dollar-pegged tokens transfer globally around the clock with no intermediary-bank chain, payouts need no local bank account, and there are no currency conversion fees when one stablecoin runs end to end. A regular bank account holds dollars fine, but moving them internationally takes days and costs real money.
How do stablecoins help businesses with cross-border payments and payroll?
Businesses can pay contractors, suppliers, and remote employees across countries without maintaining local bank accounts or navigating correspondent banking relationships. A US company paying a remote employee in the Philippines with USDC gets near-instant arrival with minimal fees, and the payer actually knows when the money lands. Employees need only a digital wallet, and the business’s cash stops sitting idle in multi-day transit.
