Scroll through any developer feed right now and you’ll watch two timelines collide: live demos of AI agents shipping code in minutes, and anxious threads about how to avoid the permanent underclass before human work hours get repriced to pennies. For almost everyone who isn’t already living off a trust fund, future labor is the single largest asset on the personal balance sheet. When machines start bidding against those hours, the panic feels rational, and the temptation to chase a four-hour-workweek shortcut gets strong.
A much cleaner way to look at the problem comes from the YouTube channel Asian Dad Energy, run by an unemployed ex-big-tech software engineer with 25 years in the tech industry whose involuntary early retirement gave him full-time hours to map out a realistic escape. Here at GeekExtreme, we pulled apart his thesis alongside the historical mobility data to see what holds up, and what a real build sheet looks like when you’re starting from zero or negative net worth.
Key Takeaways
Upward mobility in the US broke decades before generative AI arrived: roughly 90% of children born in 1940 out-earned their parents at the same age, compared with 50% of millennials, while median home prices reached roughly 5 times median household income.
Over a third of a person’s lifetime realizable wealth sits in human capital (future labor hours sold for pay, per McKinsey & Company), which means AI competition hits young workers hardest while acting as a 100x power-law multiplier that widens inequality.
Escaping wage fragility from $0 requires ignoring passive-income hype, building a 3-to-6-month emergency fund of essential expenses, clearing bad debt, and using one core AI model to build a high-trust business or acquire proven assets like diversified index funds and urban rental real estate.
Table of contents
Table of Contents
What the permanent underclass actually is
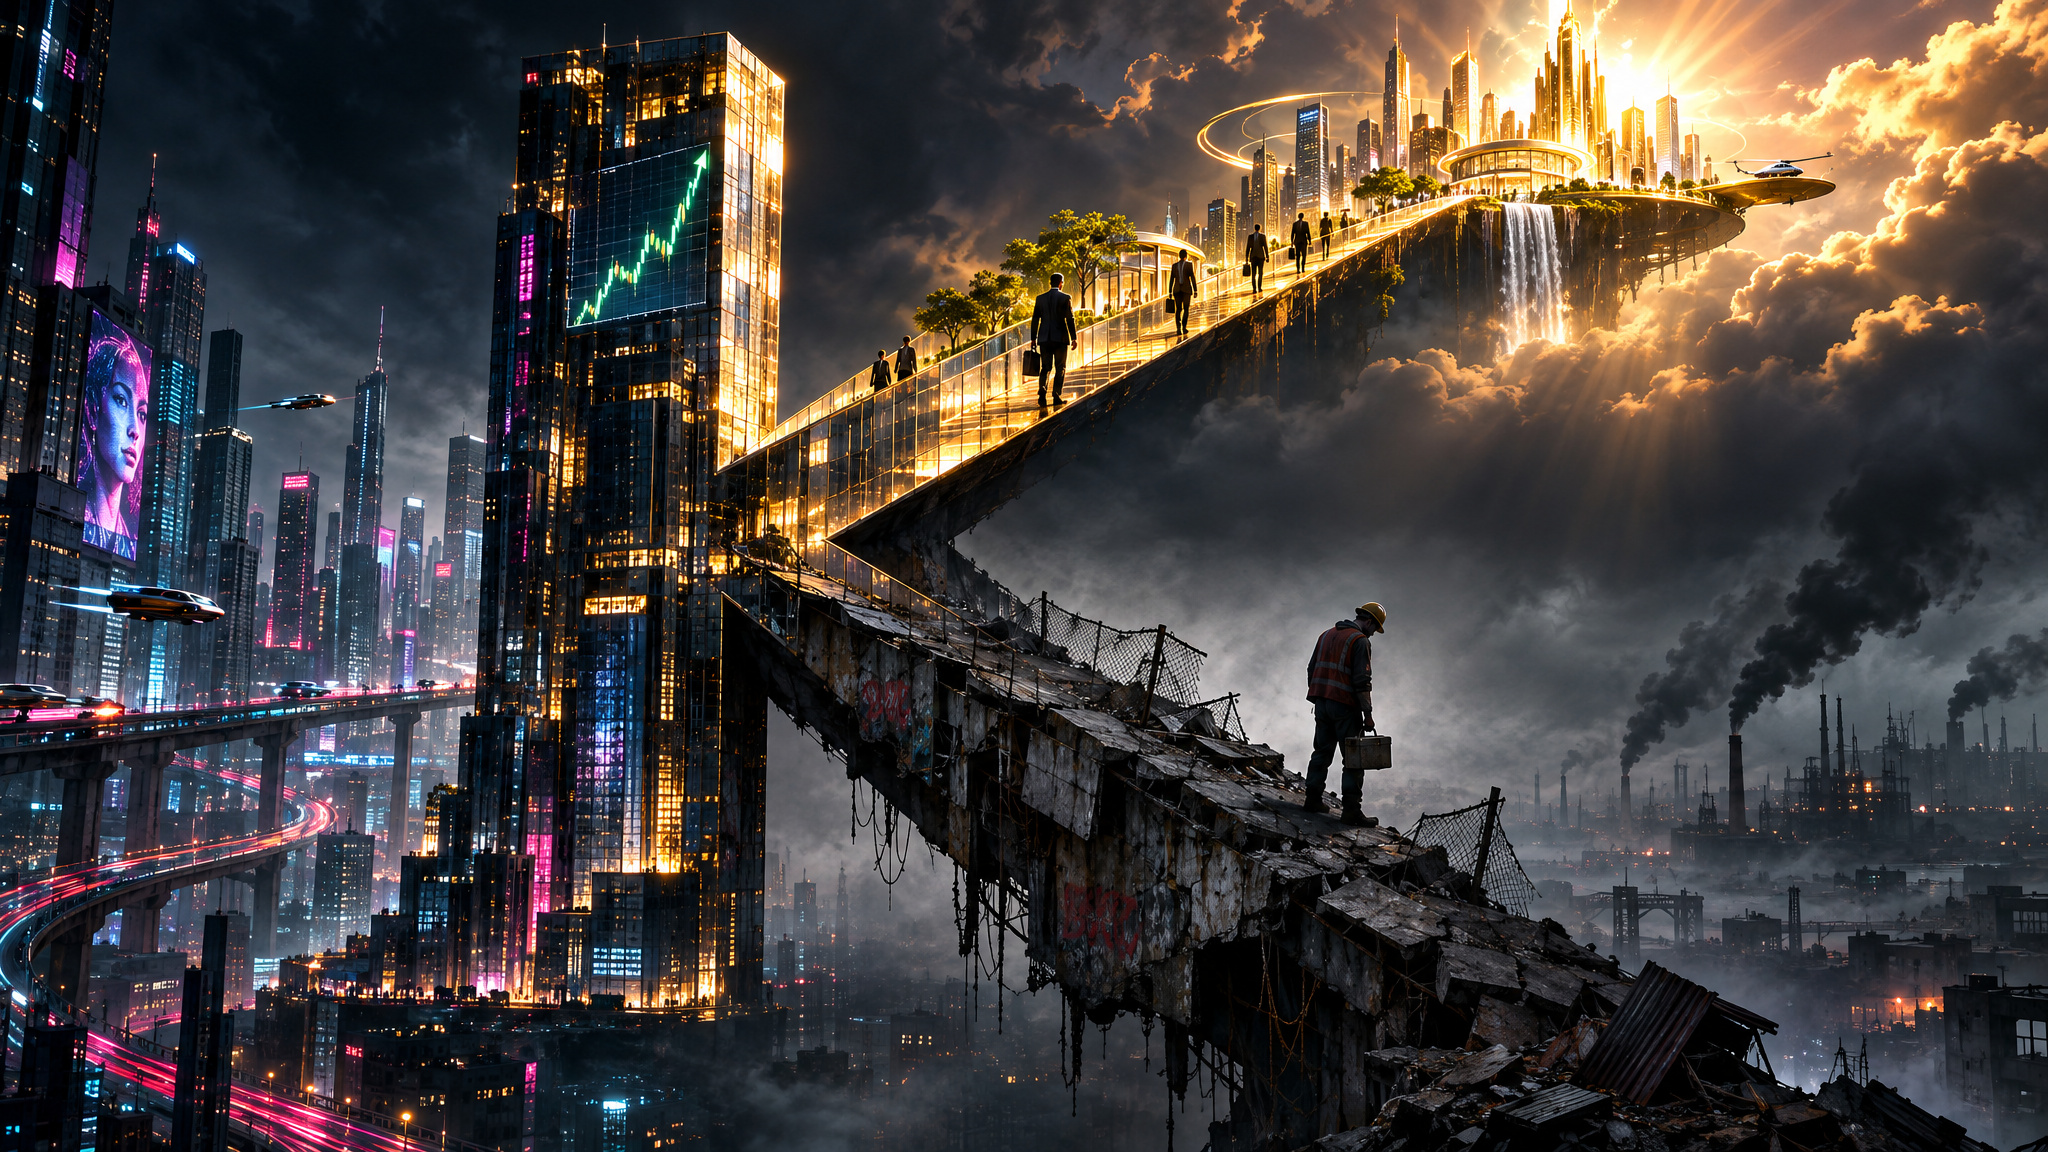
The permanent underclass is the bottom leg of a K-shaped society where wage earners watch their labor value depreciate as their bodies and minds age, while asset owners on the top leg watch capital in AI and robotics compound exponentially. Unlike economist Gunnar Myrdal’s original 1960s term “underclass,” which described long-term unemployed, underemployed, or unemployable residents cut off from society in communities hollowed out by rapid de-industrialization, the modern phrase started as a Silicon Valley joke taken too seriously. As the channel How Money Works points out, the meme puts a dystopian cyberpunk spin on the financial independence movement, treating human value as an asset on a strict depreciation schedule before machines undercut wages.
Tech insiders building generative AI fear this split most because recent history overwhelmingly favored asset owners over workers, even though Silicon Valley was once the main meritocratic escape hatch compared to finance, big law, or medicine. A Sam Altman-style prediction quoted by How Money Works claims AI will eventually do everything and make jobs optional for personal satisfaction, yet a new college graduate can already do everything right and find that, all of a sudden, there are no jobs.
If the K’s legs keep widening without triggering violent revolution or major social transformation, the bottom locks into techno-feudalism (“you will own nothing and be sad”), a historically common system that may prove more stable than our current one. The Asian Dad Energy creator speculates that most people could enter this permanent underclass within 5 to 10 years, repeating that time waits for no man.
The mobility ladder broke before AI arrived
America is already splitting into a K-shaped society where asset owners pull ahead, except in a handful of high-mobility geographic pockets. Per Raj Chetty and Harvard’s Opportunity Insights study, productivity, GDP, and corporate profits kept climbing before widespread AI, while those gains stopped reaching workers the way they used to, making automation an accelerant rather than the root cause.
What broke first: unions, housing, and education
In 1940, roughly 90% of American children earned more than their parents did at the same age, a figure that dropped to 50% by the time millennials entered the workforce. Union membership also fell from about a third of American workers to around 10% (Bureau of Labor Statistics). Workers lost bargaining power right as basic wealth-building tools drifted out of reach.
The median US home price sits at roughly 5 times median household income (Harvard’s Joint Center for Housing Studies), after home prices jumped 48% between 2019 and 2024 while household incomes rose 22% (Federal Reserve data). Meanwhile, inflation-adjusted education costs climbed 312% since 1963 (Education Data Initiative), leaving the average federal student loan borrower starting adulthood in a $39,633 hole (Department of Education).
Where the ladder still works: San Jose vs. Charlotte
Most underclass advice completely ignores geography, even though upward mobility chances vary by a factor of three across US locations. According to Harvard’s Opportunity Atlas, a child born in the bottom income fifth in San Jose has a 12.9% chance of reaching the top fifth by age 30. In Charlotte, North Carolina, that figure drops to 4.4%. Silicon Valley is one of the last places the traditional ladder still functions.
Human capital on a depreciation schedule
According to a McKinsey & Company report, over a third of a person’s lifetime realizable wealth is tied up in human capital: future hours of labor traded for money, unless you’re already independently wealthy. When AI enters the market as a viable competitor for human work hours, that human capital goes on a steep depreciation schedule, hitting young people hardest because they have the most future hours to sell and the least time to build alternative cash flows.
As Substack writer Jordan McKinney notes in a discussion on The Omega Point, AI acts as a power-law multiplier that drives rising inequality. Give a 100x multiplier to someone at productivity 100 and they reach 10,000, while someone at 3 reaches 300. Net wealth rises, but the gap between them explodes.
The easy-money fantasy economy, debunked
Passive income from ebooks and AI businesses is a marketing myth sold by financial influencers and internet gurus, rather than a shortcut around the long, difficult work of building real asset ownership. Escaping downward mobility means shifting from trading time for money to owning productive assets. Yet a whole genre shaped by figures like Tim Ferriss and Alex Hormozi packages that transition as effortless cash flow. In practice, a $20 ebook will not make you rich, AI will not magically automate a business to profitability, and passive income is rarely passive.
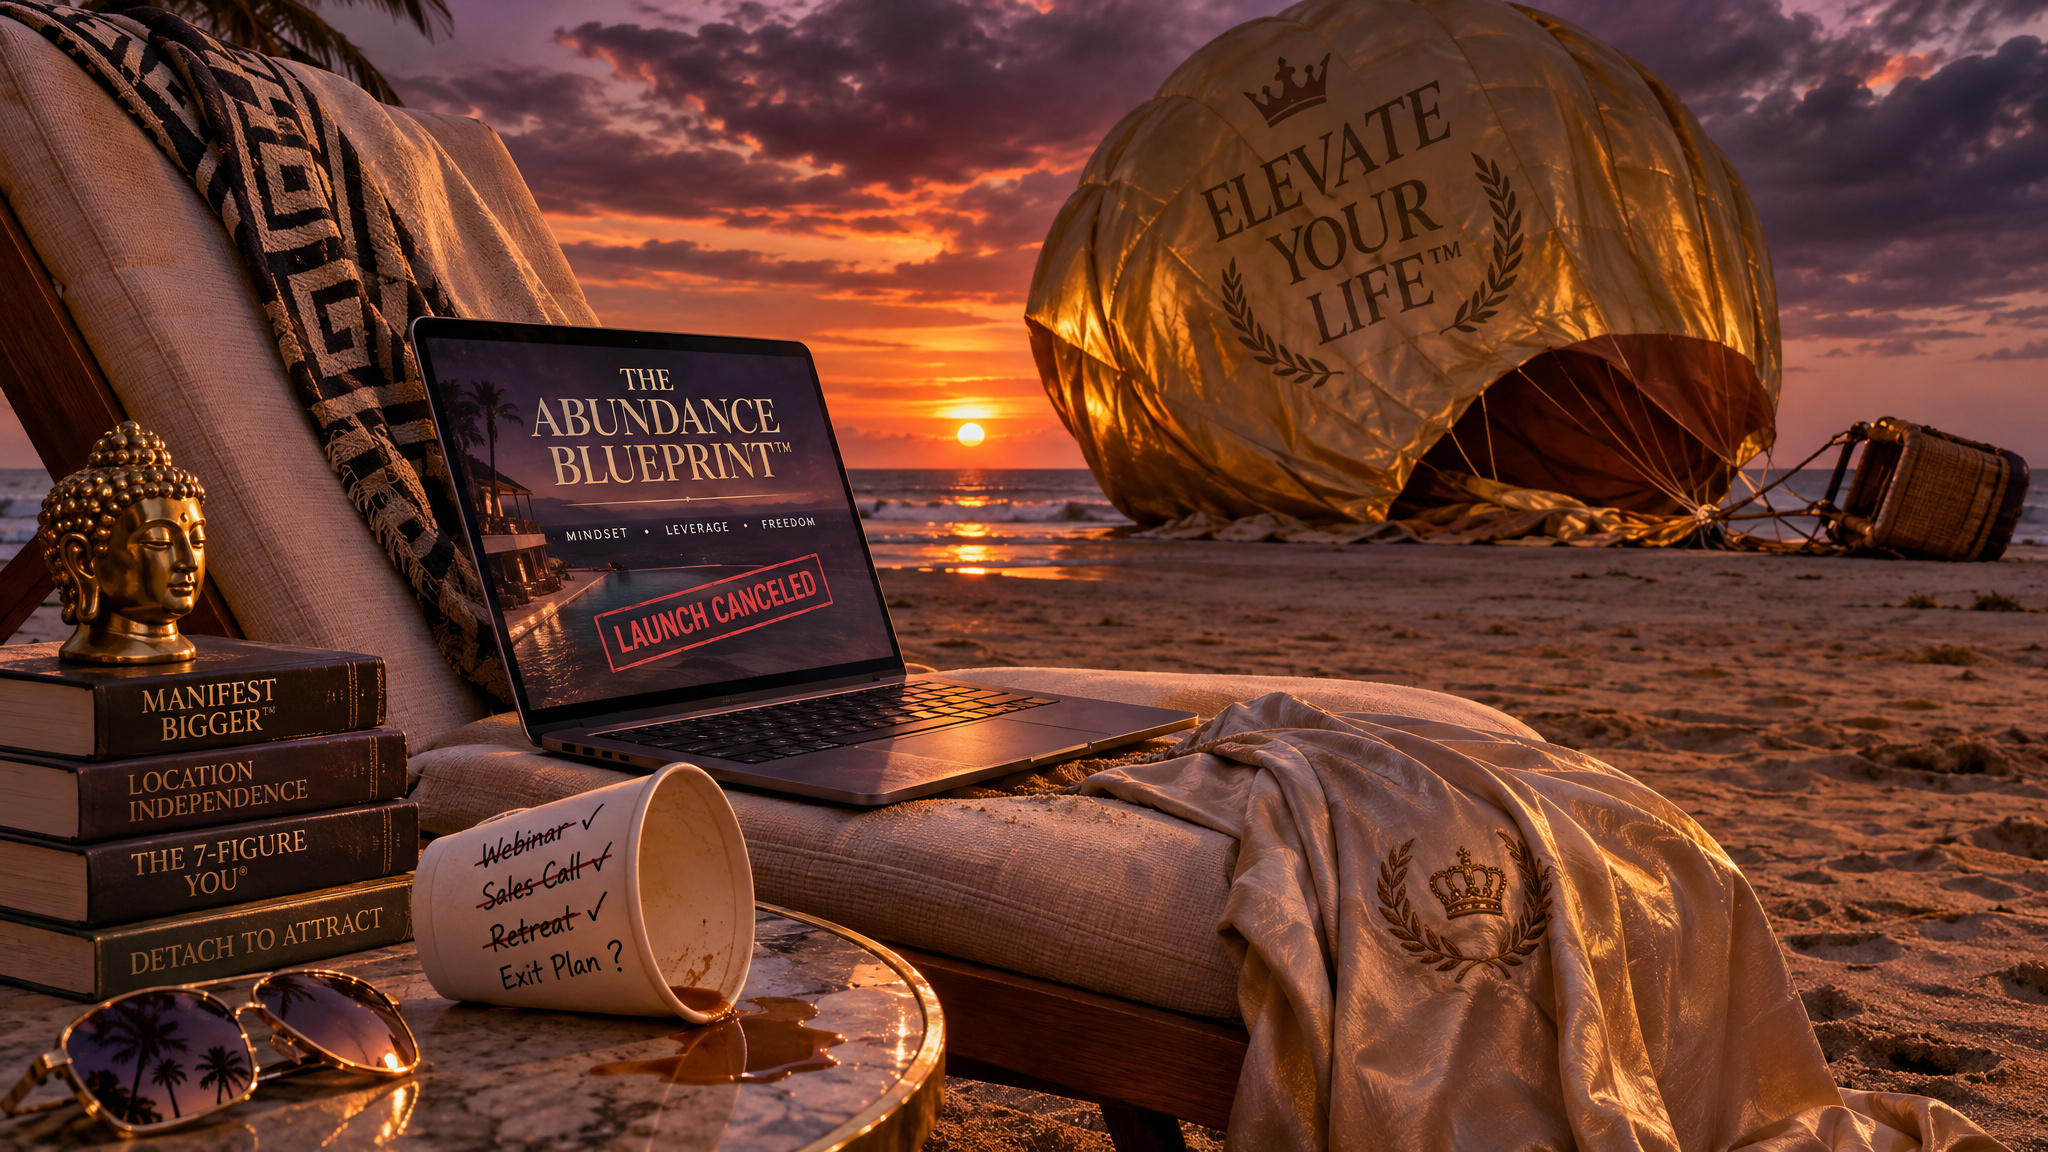
Alongside the $20 ebook, the standard guru catalog leans on three recurring templates. You can buy a speculative investment like an NFT promising a 1,000% return per year, or work 4 hours per week from a laptop on a beach making $1 million a year. The latest pitch is an AI-powered business pulling $100K in monthly recurring revenue while you sleep. That kind of NFT speculation is not real asset ownership; it is just gambling with extra steps.
With the others, the pattern is always the same: someone spins up an ebook, AI storefront, or token in a weekend burst of enthusiasm, watches initial traction stall out, and abandons the project the moment “passive” income demands daily marketing, iteration, and customer support. As the How Money Works host (a self-described former finance bro) points out, heavy Silicon Valley buzzword inflation, from move fast and break things, building in public, minimum viable personality, vibe coding, and 10x to AI native, cloud native, cryptonative, post scarcity, post abundance, postnut pre-revenue, pre-idea, “Uber for agentic software,” and “as a service,” usually just signals a startup desperate for another funding round.
The realistic path from $0: stability first
Building wealth from zero savings means getting basic financial stability locked in before you chase financial independence, and it’s not too late if you’re starting in debt with a negative net worth. Financial independence simply means owning enough financial assets to survive without a job, achieved by living below your means, solving valuable problems others pay for, and investing the surplus. When you start at $0 or in the red, escaping wage fragility requires a strict four-step sequence:
- Audit all expenses, income, and debt to see your true starting point.
- Separate essential living costs (housing, food, utilities) from optional spending.
- Calibrate a personal sustainable frugality threshold so you spend less than you earn and pocket the difference.
- Build an emergency fund of 3 to 6 months of essential expenses, then pay down and pay off debts.
Audit your true starting point
People auditing their spending for the first time routinely discover recurring lifestyle costs blurring the line between essential and optional, set an extreme starvation budget they can’t hold, and abandon the plan within weeks.
Find your sustainable frugality threshold
Extreme frugality can go as far as cutting subscriptions, restaurants, consumer goods, or even heat and meat, but human beings need creature comforts and tolerances shift over time. Your sustainable frugality threshold is a personal calibration problem, not a discipline contest.
Emergency fund, then debt payoff
Once your sustainable frugality threshold is set, use the savings to build a 3-to-6-month emergency fund. That buffer keeps a single bad surprise from wrecking your balance sheet so you can attack and eliminate your debt.
Create value and own an income engine
With focused effort, you can master a concrete skill like engineering, marketing, sales, or management in less than a thousand days. The value-creation formula is straightforward: find a real, difficult problem, get good at solving it, and get paid for the value created. Relying on a job still leaves you on the wage-earning bottom leg of the K even with a high salary, so the realistic escape from downward mobility is owning an income engine that makes money without directly consuming your labor.
Where a traditional job caps your upside at rented hours, an income engine is a business you control entirely, and that is what bridges the gap to financial independence. Modern technology has stripped away the old gatekeeping, letting you build a business and reach customers without permission from gatekeepers, a prestigious degree, or decades of experience.
Think of civilization as a giant cruise ship or ocean liner where the engine room, electricity, and plumbing are all half broken; in the optimistic AI scenario, the ship gets upgraded, and you get paid by picking a broken system to fix. If entrepreneurship isn’t your play, entrepreneur Colin Stuckert notes one viable alternative: get so exceptionally good at a skill that a company hires you, pays you a massive salary, and hands you stock options.
What to own first when you have little money
High-probability, value-preserving assets are what you should own first once you have savings to invest, rather than speculative lottery tickets or depreciating lifestyle purchases. In a hyper-capitalist system, you escape wage fragility by putting every dollar of surplus into broad-market index funds and cash-flowing assets that hold their value and compound. Drawing strictly from his own personal experience, the Asian Dad Energy creator points to three favored asset classes: rental real estate near major urban centers, large diversified index funds, and ownership of businesses he knows very well where he holds an asymmetric advantage, while he’s quick to remind listeners he’s no financial advisor, and that his personal picks deserve a grain of salt.
Good debt vs. bad debt
Before buying a single share or property, you have to separate good debt from bad debt. Good debt borrows capital to acquire productive assets or grow a business with a high probability of preserving value and generating a return. Bad debt funds low- or zero-return items that depreciate in your driveway or closet: status symbols, lifestyle upgrades, and what the creator calls “man toys.” The underlying rule is ruthless and simple: never spend money on things that don’t generate future returns.
The source’s three favored asset classes
For someone starting with small capital, those three asset classes carry different entry requirements, and none of them resemble the effortless passive-income fantasies debunked earlier. Large diversified index funds require almost zero operational overhead and let a beginner buy a slice of the top leg of the K as soon as their emergency fund and bad debt are handled.
Rental real estate near major urban centers demands heavier upfront capital, careful underwriting of good debt, and a stomach for physical property management, trading liquidity for cash flow and urban land scarcity. Buying or building a business you know deeply is the upside play, but it only works when you bring an asymmetric advantage from skills you’ve mastered, rather than blindly copying an internet guru’s template.
Why ‘learn AI’ is not enough
Deep, workflow-level AI integration is how you use AI to increase your income before automation replaces your skills, because casual prompting leaves you in the exact same tier as everyone else. Using AI as a real output multiplier means wiring models into continuous daily production rather than treating them as a novelty search bar.
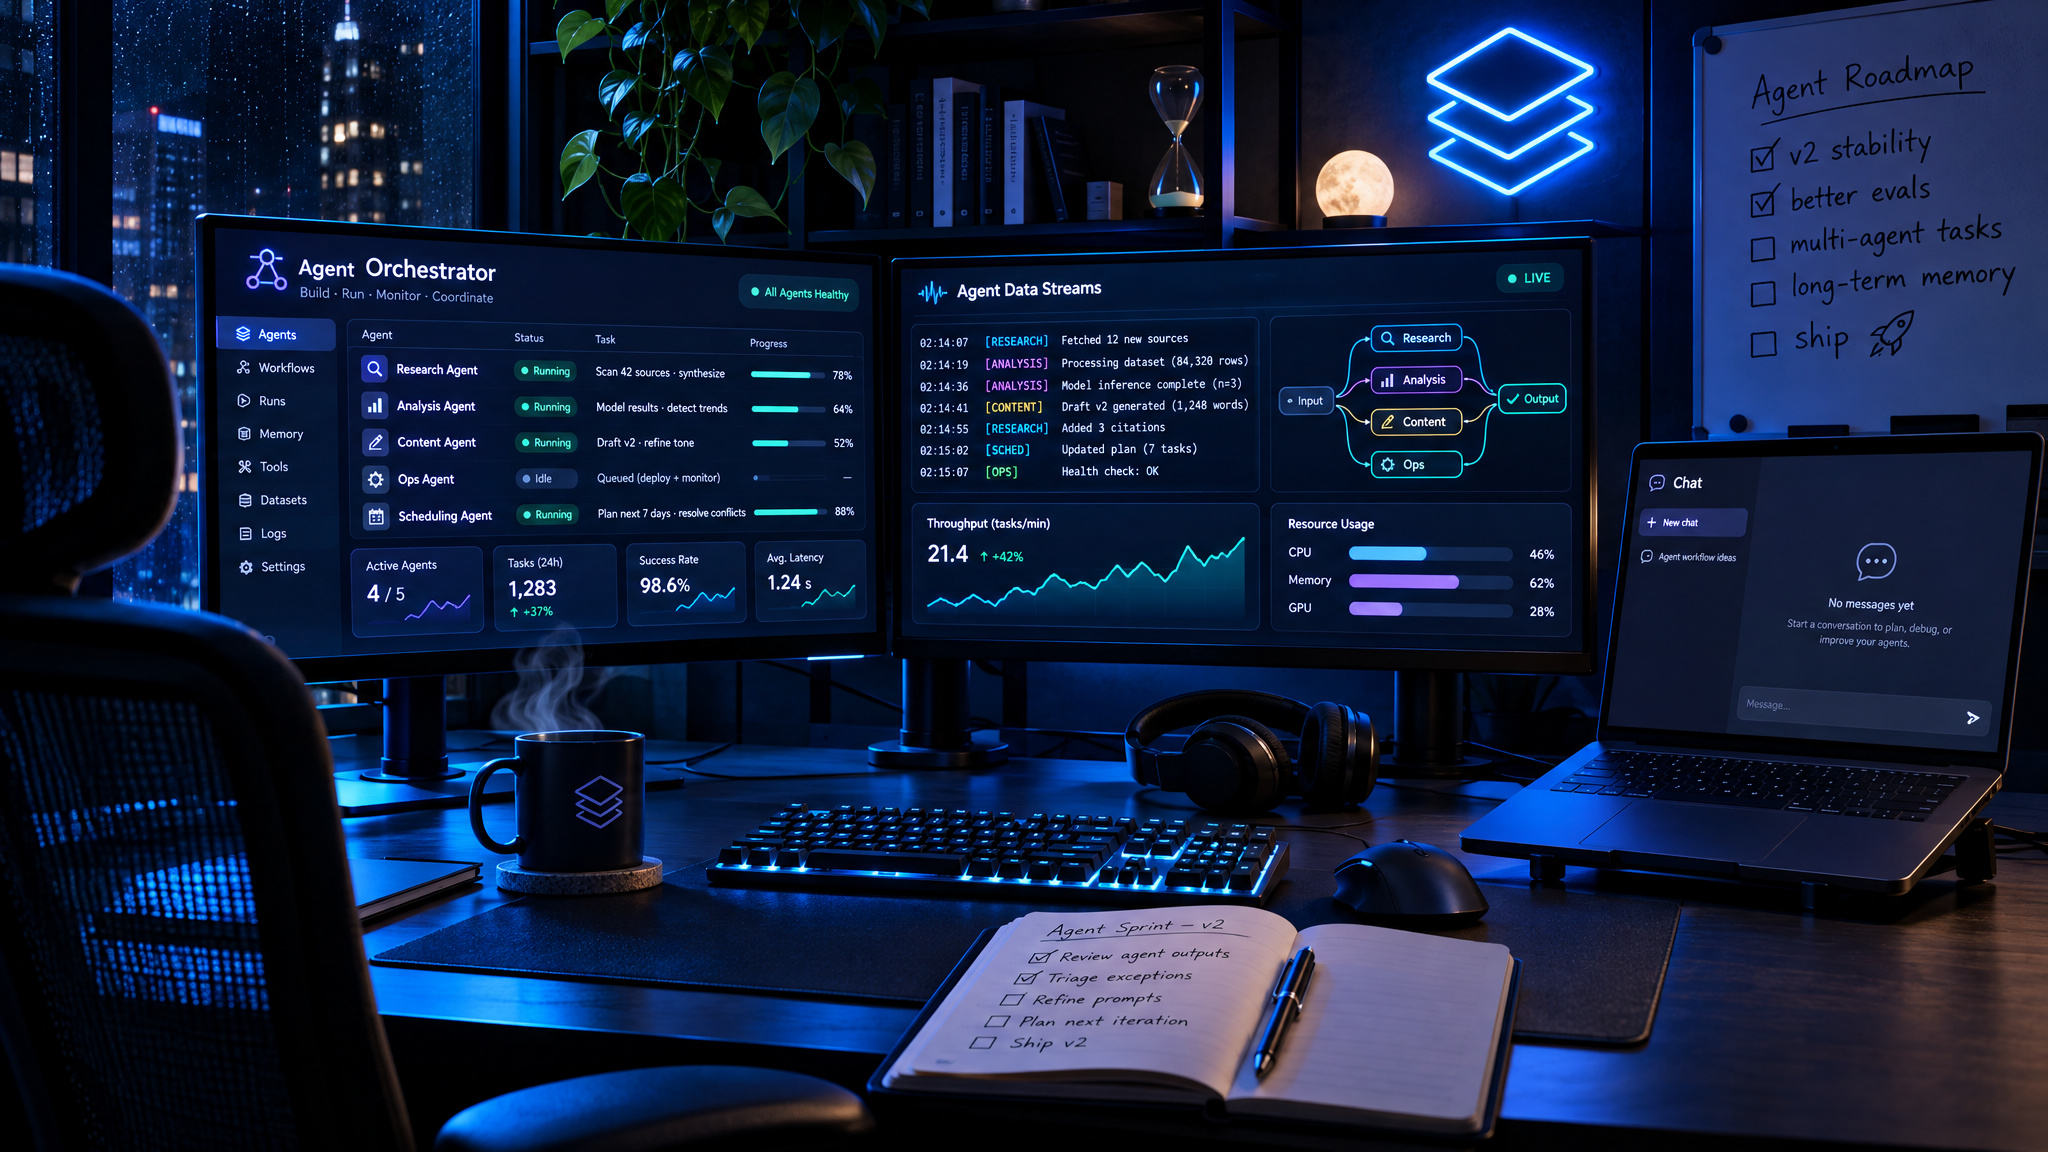
In practice, adoption depth is split between a free-tier majority using chatbots like Google for basic factual Q&A or as a sycophantic therapist and life coach, and a tiny bleeding-edge minority running agents 24/7 with tools like OpenClaw to get orders-of-magnitude productivity leverage and build zero- or one-person companies. One supposition from The Omega Point discussion, a rough heuristic, not measured data, says frontier lag compounds fast: sitting 1 year behind the AI frontier makes you 4x less effective, sitting 2 years behind makes you 16x less effective, and every 6 months AI may add another 2x to creative or productive output.
The frontier-lag penalty
That gap between frontier lag and adoption depth shows up every day when two people with access to the exact same models end up orders of magnitude apart, simply because one opens a chat window once a week and concludes AI is overhyped while the other wires agents into daily workflows and compounds the output. A viral tweet captured the split perfectly: on one side, Anthropic is hypothetically running 10,000 mythos models in parallel to hunt software exploits; on the other, “your sister” is using Microsoft Copilot with a haiku-sized model and deciding AI is all hype.
That exact gap is why, here at GeekExtreme, I’m actively trying to learn as much about using AI as effectively and quickly as possible, and earn as much money as possible while I’m still able.
S curves are compressing
Waiting to see how the dust settles is dangerous because technological S-curve compression is accelerating AI adoption speed past every historical benchmark. Every major technology follows an S curve: a slow gradual start, a steep maximum-rate climb, and final saturation. Electricity, the telephone, and cars each took multiple decades to reach 50% adoption. The internet compressed that S curve and hit 50% adoption in roughly 10 years. Because AI stacks directly on top of existing smartphones, computers, and internet infrastructure, it is the technology in history.
Will AI really take the jobs?
AI’s threat to your job and labor value over the next 5 to 10 years comes down to two variables: does rising efficiency trigger Jevons paradox or hit fixed demand, and do you work on a screen or in the physical world? Because human capital represents over a third of lifetime realizable wealth (per McKinsey & Company), it is hard to project what the future will look like and some companies are just using AI as an excuse, a practice known as “AI redundancy washing,” so claims about AI-driven change should not be taken at face value. Hands-on workers in the physical world will be fine in the short term until robotics becomes capable.
Software developers are the canary in the coal mine: the most sophisticated AI users whose industry was transformed almost overnight by LLMs. The standard mass-layoff math assumes fixed demand (10x coder efficiency means 10x fewer coders needed), whereas Jevons paradox shows that making production more efficient can increase total demand by 10x or 100x instead. Developer jobs may plausibly segment into expert code auditors who inspect AI-written code and less-technical builders with great user sense who ship working products. Across the board, five traits win in the AI paradigm: intelligence, agency, creativity/taste, speed, and computer skills, with taste becoming the ultimate bottleneck as AI commoditizes raw engineering work.
Distribution and trust: the real moat
A one-person business or personal brand works in the AI age for builders willing to show their face, build human relationships, and own a distribution channel. As Colin Stuckert argues, distribution is the number-one moat: within 12 to 24 months, practically everything online will be AI-generated and people won’t know what to trust, pushing buyers back to personal networks where brand, relationships, and getting on camera or sales calls win the deal. Roughly 20 years ago, Kevin Kelly calculated that 1,000 true fans who buy whatever you produce can generate $100,000 a year, and even though millions of creators, freelancers, Etsy sellers, and info-product builders already run one-person businesses, that opportunity hasn’t even started yet once paired with an authentic distribution moat.
What you don’t need is the absurd 7-model tool stack Stuckert mocks: Codex app 5.5 medium on fast mode, Hermes agent powered by a local model, OpenClaw GPT 5.5 olaf, Gamma 4 on a Mac Mini, GPT 5.5 pro, Claude, and Gemini. Pick one core model (ChatGPT or Claude), plug a $100 HDMI monitor into your Mac (a practical dual-screen trick from Stuckert’s multi-monitor online poker days, though context-switching while running agents gets exhausting), and pour your saved energy into human persuasion across channels like Amazon, eBay, Etsy, social media feeding a ManyChat funnel, or cold email plus sales calls.
The deadline-refrain hype machine
How long it realistically takes to reach financial independence starting from nothing is not established with concrete math anywhere in the underclass debate; the only grounded reality is that it is a difficult, long-term undertaking. Everything else on your feed is a rhetorical timer designed to spike your cortisol.
Walk through San Francisco via the satirical AI-billboard-walk videos on The Omega Point and you’ll hear the countdown shrink in real time: first You have 18 months to escape the permanent underclass. Lock in., then “6 months”, and finally “zero months, there is no class.” It’s pure AGI-era meme culture, stitched together from “It’s so over / We’re so back” mood swings, “Stop hiring humans” and “Do not nerf. Made in San Francisco.” billboards, model usage limits, “cashmere the immortals,” TC stack badges, and talk of escape velocity 11.2 or longevity escape velocity (gaining one year of life back for every year lived). Even the Asian Dad Energy creator’s 5-to-10-year window from earlier is explicitly his own speculation, yet the underlying message behind the satire holds up: stop doomscrolling the countdown and start building.
What escaping the underclass doesn’t fix
If social mobility becomes impossible and society locks into the stable techno-feudalism described earlier, escaping into the asset-owning class still leaves you facing a deep philosophical meaning crisis and heightened geopolitical risk, even if AI solves material scarcity. In the optimistic scenario where practical problems vanish and universal basic income (UBI) arrives, the existential weight gets heavier, like the comic where a new adult realizes “I can do anything I want,” asks “What do I want?”, and expires still asking that question.
Creatively and culturally, the same AI pipeline splits in two: it hands a solo creator a full production team so today’s Stanley Kubrick can make high-fidelity art on a low budget without pitching a studio, while simultaneously flooding the internet with dopamine-spiraling, parasitic junk content. In Friedrich Nietzsche’s framing of last men and supermen, the majority risks getting swallowed by infinite AI consumption while a tiny fraction builds. At the macro scale, AI accelerates the illuminated frontier of human knowledge until the share of people who can keep up shrinks toward zero (Goethe is often cited as the last universalist across biology, math, literature, and science) and drives rapid civilizational divergence, such as a hypothetical AI-powered Chinese empire realizing its 2100 vision in 5 to 10 years, raising the risk of conflict and war.
Master the technology: the author’s own play
My own play is simple: I’m trying to learn as much about using AI as effectively and quickly as possible, and earn as much money as possible while I’m still able. Waiting for regulation or Tristan Harris-style collective restraint (“if everyone would just” live their anti-AI values) is a dead end when, as Marc Andreessen observed, people say they dislike AI and then use it daily. Stop consuming content, endlessly preparing, and making excuses; instead, live below your means, solve valuable problems others pay for, and put the surplus money to work generating more money.
Frequently Asked Questions
What is the permanent underclass and why are Silicon Valley insiders warning about it?
In tech circles, the permanent underclass refers to the lower tier of a K-shaped economy where ordinary workers see the value of their labor steadily drop as AI and robotics compound wealth for capital owners. It started as a dark Silicon Valley meme riffing on financial independence—treating human work hours like a depreciating asset that machines are about to undercut—unlike Gunnar Myrdal’s 1960s concept of communities gutted by de-industrialization. Insiders building generative AI are sounding the alarm because the modern economy already rewards asset holders over wage earners, and they worry automation could permanently lock everyone else into techno-feudalism within 5 to 10 years.
How can I build wealth from nothing when I am starting with zero savings?
You have to lock down basic financial stability before chasing big investment returns. Start by auditing every dollar of income, spending, and debt to separate true essentials like housing, food, and utilities from disguised lifestyle habits. From there, calibrate a sustainable frugality threshold you can actually stick to without burning out, save up a 3-to-6-month emergency fund of essential living costs, and wipe out your high-interest bad debt before investing your surplus.
Is it too late to escape the underclass if I am already in debt with negative net worth?
No, starting in the red does not lock you out, considering the average federal student loan borrower already begins adulthood $39,633 in the hole. The key is ruthlessly cutting off bad debt—borrowing for depreciating status symbols, lifestyle upgrades, and “man toys”—while you build a 3-to-6-month cash buffer of essential expenses. Once that emergency shield is in place to keep a single bad surprise from wrecking your progress, you can systematically pay off what you owe and redirect your cash flow into productive assets.
Between financial independence and relying on a job, which is the realistic escape from downward mobility?
Financial independence is the only durable escape because relying on a paycheck keeps you on the wage-earning bottom leg of the K-shaped economy, where your income is capped by the hours you rent out. Escaping downward mobility means owning an income engine—a business you control or productive assets that generate cash without directly consuming your time. If building a company isn’t for you, the only viable job-based alternative is mastering a difficult skill in under a thousand days so thoroughly that an employer hands you both a massive salary and equity.
What assets should I own first if I have little money to invest?
Once your emergency fund is full and your bad debt is gone, put your early capital into high-probability, value-preserving assets rather than speculative lottery tickets. Large, diversified broad-market index funds are the cleanest starting point for small budgets because they require almost zero operational overhead and immediately give you a compounding slice of the asset-owning economy. Later on, as your capital and skills grow, you can look into higher-barrier plays like rental real estate near major urban centers or buying into businesses where you hold a genuine skill advantage.
Will AI really take my job and devalue my labor in the next 5 to 10 years?
That depends on whether you work on a screen or in the physical world, and whether AI-driven efficiency hits fixed demand or triggers Jevons paradox by expanding total demand 10x or 100x. Physical, hands-on trades are relatively insulated in the short term until robotics catches up, and some corporate layoffs right now are just “AI redundancy washing” to cover standard cost-cutting. For screen-based workers like software developers, raw technical execution is getting commoditized fast, shifting the real career advantage to people who combine deep workflow-level AI integration with high agency, speed, and human taste.