Stablecoins vs altcoins comes down to one variable: volatility. Altcoins are every cryptocurrency built to ride price movement and network adoption; stablecoins are engineered to erase that movement, holding steady near a fixed value like real money so value can move without the price roulette. One class embraces the swing, the other designs it out of the system, and everything else in this piece is a consequence of that single design decision.
The scale on each side looks wildly different.Stablecoins are a roughly $306 billion market dominated by Tether and USDC, sitting inside a broader altcoin sector where over 200 stablecoins alone exist, before counting any of the volatile coins. And here’s the thing that made me sit up when I was digging through the 2026 data: “stablecoin” is not a monolith either. RLUSD, Ripple’s dollar token, is up 86% year-to-date, opening the year at $1.336 billion and hitting a $2.44 billion record on September 14.
PYUSD, PayPal’s dollar token, is down 22% year-to-date from a $4.214 billion peak on March 5.Same category, same “stable” label, opposite trajectories. A $75.3 billion figure also appears in the source data with an unclear referent, so I’m flagging it rather than guessing what it measures.
The path from here: definitions for both classes, the volatility-vs-stability split, how each type works mechanically, where the risks actually sit, and what the 2026 numbers say about whether either label describes a coherent thing. Spoiler: they don’t, and the numbers inside the “stable” category are already disagreeing with each other.
Key Takeaways
Altcoins are any cryptocurrency other than Bitcoin, spanning meme coins like Dogecoin to core infrastructure like Ethereum and Solana; stablecoins are pegged assets built to hold steady value for payments and settlement.
In Q2 2026, crypto fell 12.6% to $2.1 trillion while stablecoins contracted only 1.6% to $305.1 billion, their first quarterly contraction since Q3 2023, which CoinGecko read as capital leaving the industry rather than rotating into stablecoins.
Issuer and chain data show neither class is uniform: RLUSD grew 86% YTD while PYUSD fell 22%, and RLUSD’s share on XRPL, the ledger behind how to buy XRP, dropped from 58.9% to roughly 43-44% as Ethereum’s rose to about 56%.
Table of Contents
What are altcoins?
Altcoins are any cryptocurrencies other than Bitcoin (BTC). That’s the whole definition, and the name is just a smushed “alternative” and “coin.” Quick etymology aside, done.
The term has outgrown its origins, though. It started life describing Bitcoin forks. Modern usage is broader: digital assets issued across many blockchains, which is how one category ends up holding a joke dog coin and the settlement layer for billions in DeFi. Named examples give you the spread: Dogecoin, Solana, Litecoin, Ethereum, Shiba Inu, Cardano. No ranking implied; that’s meme coin on one end and serious infrastructure on the other, with a lot of weird in between.
And anyone can create one.The barrier is basically zero. That’s fun as a “the system is open” observation, and it’s also quiet setup for a problem we’ll hit in the risk section: an ecosystem where deployment costs nothing is an ecosystem flooded with wildly varying quality.
Bitcoin is excluded by definition, which surprises people. It’s the reference point the category is defined against, not a member of it.Ethereum isn’t a stablecoin either, for what it’s worth; it’s the leading altcoin, and it earned that position the same way Solana did: by shipping the smart contracts that enabled NFT purchases and DeFi participation. Smart contracts enabled NFTs and DeFi, developers built on top, and usage pulled value. The category’s real story is simpler than any ranking: altcoins do what Bitcoin can’t, smart contracts, DeFi, NFTs, lower fees, and the ones that survived did it by being useful.
You’ll also hear “altcoin season” thrown around, the community’s hope that altcoins collectively outperform Bitcoin for a stretch.Treat it as a known community phenomenon with a wink, not a strategy.
What are stablecoins?
Stablecoins are digital assets pegged to an external reference, fiat currency, commodities, sometimes crypto collateral, engineered to hold steady value for payments and settlement. They hold constant value across bear and bull markets, and there are over 200 of them, which is more of these things than most people assume.
One classification wrinkle: calling stablecoins a type of altcoin is not exactly right. Technically they’re issued like altcoins, but the volatility distinction is what matters, so they function as a separate class. The cleanest edge case is on the XRP Ledger: XRP is an altcoin, the native token of that chain, not a stablecoin, even though Ripple issues the RLUSD stablecoin on that same chain. That’s one network hosting both classes side by side, a detail most explainers skip. And since an altcoin is just any cryptocurrency other than Bitcoin, XRP qualifies on definition alone, the volatility distinction is what keeps it out of the stablecoin class.Stablecoins, meanwhile, are the bridge between traditional finance and the onchain world, the boring-on-purpose part of crypto, and that’s the point.
Key differences: volatility vs stability
The decisive difference is each class’s relationship with volatility. Altcoins are growth and utility instruments whose price tracks network adoption; volatility is a feature for traders and a bug for storing value. Stablecoins prioritize capital preservation: value must stay near the peg, ideally $1.00, so institutions can settle a transaction without the value shifting mid-flight.
| Altcoins | Stablecoins | |
|---|---|---|
| Purpose | Growth and utility; price tracks network adoption | Capital preservation; payments and settlement |
| Price behavior | Swings with sentiment, adoption, and macro news | Holds near peg, e.g. $1.00 |
| Risk shape | Continuous price exposure; quality varies wildly | Binary tail events: de-pegging, custodian failure |
| Suits | Traders and DeFi participants | Anyone moving value who doesn’t want a price bet |
Now stress-test the stability claim with Q2 2026 data.Crypto overall fell 12.6%, from $2.4 trillion to $2.1 trillion, while stablecoins contracted only 1.6% to $305.1 billion, the sector’s first quarterly contraction since Q3 2023. CoinGecko read that as capital leaving the industry entirely rather than rotating into stablecoins. So stability held up relatively, but even the calm corner shrank. Lower volatility, not immunity.
Types of altcoins and what gives them value
Altcoins fall into three functional categories. Native tokens like ETH and SOL pay gas and transaction fees on their chains; they’re the fuel, and anyone who’s paid a gas fee feels this one immediately. Governance tokens grant DAO voting on protocol upgrades and treasury allocations; concretely, holding one can mean voting on changing a lending market’s risk parameters. Utility tokens unlock access to a specific service, which is kind of elegant: think of it as an API key you can trade.
Most altcoins follow the ERC-20 standard, which is the lego-brick beat: a shared standard means instant compatibility with DEXs and lending protocols without any custom work.
Smart contracts govern the tokenomics, max supply, inflation rates, distribution schedules, the config file for a coin’s economy. The theory says altcoin value ties to protocol utility: more layer-1 usage should raise demand for the native token. But 2026 shows the loop decoupling.XRP sits near $1.49, down about 19% since Jan. 1, despite XRPL stablecoin and tokenization growth.
Usage up, price down. That’s an observed gap, not a law, and I’m not going to pretend it predicts anything.
Types of stablecoins and how the peg holds
Stablecoins fall into three main backing models.Fiat-collateralized coins are backed 1:1 by fiat sitting in a bank account, currently the most widely used form; the issuer holds offchain liquid reserves like cash and treasuries matching the tokens minted onchain, and USDT and USDC pegged 1:1 to the U.S. dollar are the canonical examples. The trust location is honest to name: onchain tokens, offchain collateral, and you’re relying on the paperwork being real.
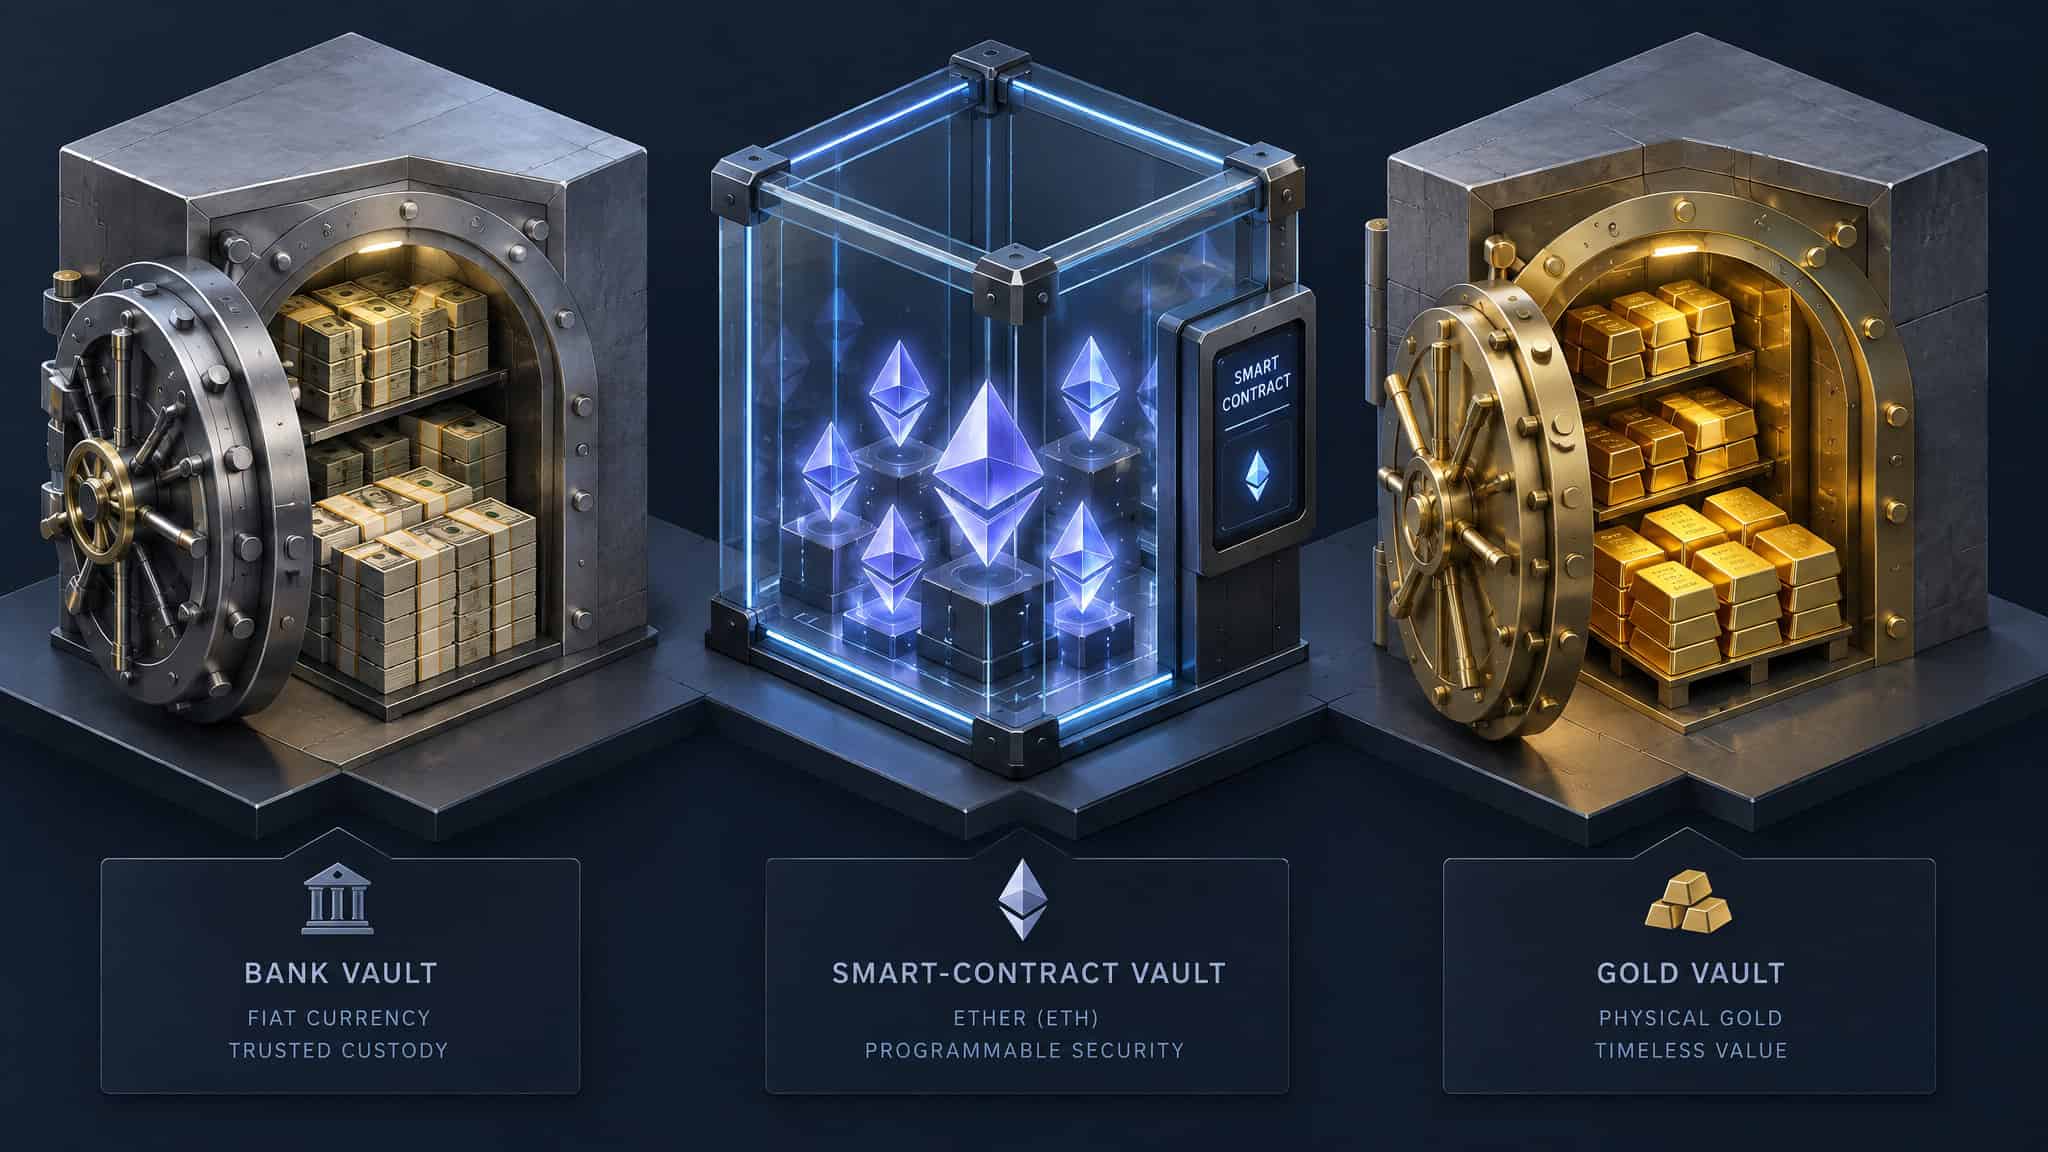
Crypto-collateralized coins lock volatile assets like ETH in smart contracts, over-collateralized to buffer price drops; Dai (DAI) is the example, and it’s the least favored form precisely because the backing itself is volatile. Commodity-backed coins peg to real-world assets, gold being the most common, with oil and real estate also cited, representing ownership of the physical underlying.
There’s a genuine disagreement here worth attributing both ways. The neutral framing says fiat-backed is the most widely used. A video explainer critiques fiat-backed coins as “fiat proxies” that expose holders to inflation of the reserve currency, naming the USD, GBP, euro, and yuan. Both stances are documented and they flatly disagree; I’m not picking a winner.
Under the hood: smart contracts and the oracle layer both classes share
Both classes are smart-contract artifacts: altcoin contracts encode scarcity rules while stablecoin contracts encode peg-defense rules connecting onchain minting to offchain reserves. Since blockchains can’t natively see offchain data like prices or bank balances, both depend on oracle infrastructure, with Chainlink as one named example: Data Feeds price Aave lending collateralization and liquidations, Data Streams serve derivatives at low latency, Proof of Reserve verifies custodian balances onchain to prevent fractional-reserve minting, CRE orchestrates issuer workflows, and CCIP enables cross-chain transfers. The real dividing line isn’t the assets; it’s the shared data layer underneath them.
Use cases: DeFi growth engine vs payments rails
People hold stablecoins because they remove currency risk: neither side of a payment is betting on a price.That makes them the obvious fit for remittances, B2B payments, and payroll, and major financial institutions are exploring them for instant settlement bypassing traditional banking rails. The in-progress institutional case is the interesting one: in August, Ripple, Clearpool, and Cicada Partners were building an XRPL lending market with RLUSD as the credit asset, and earlier in September Ripple outlined RLUSD’s regulatory structure as institutions weighed the token. Frame all of that as being built, not shipped. The pattern is that the stablecoin stops being a cash equivalent and becomes the credit asset itself. RLUSD sitting at the center of a lending market, not just a settlement balance.
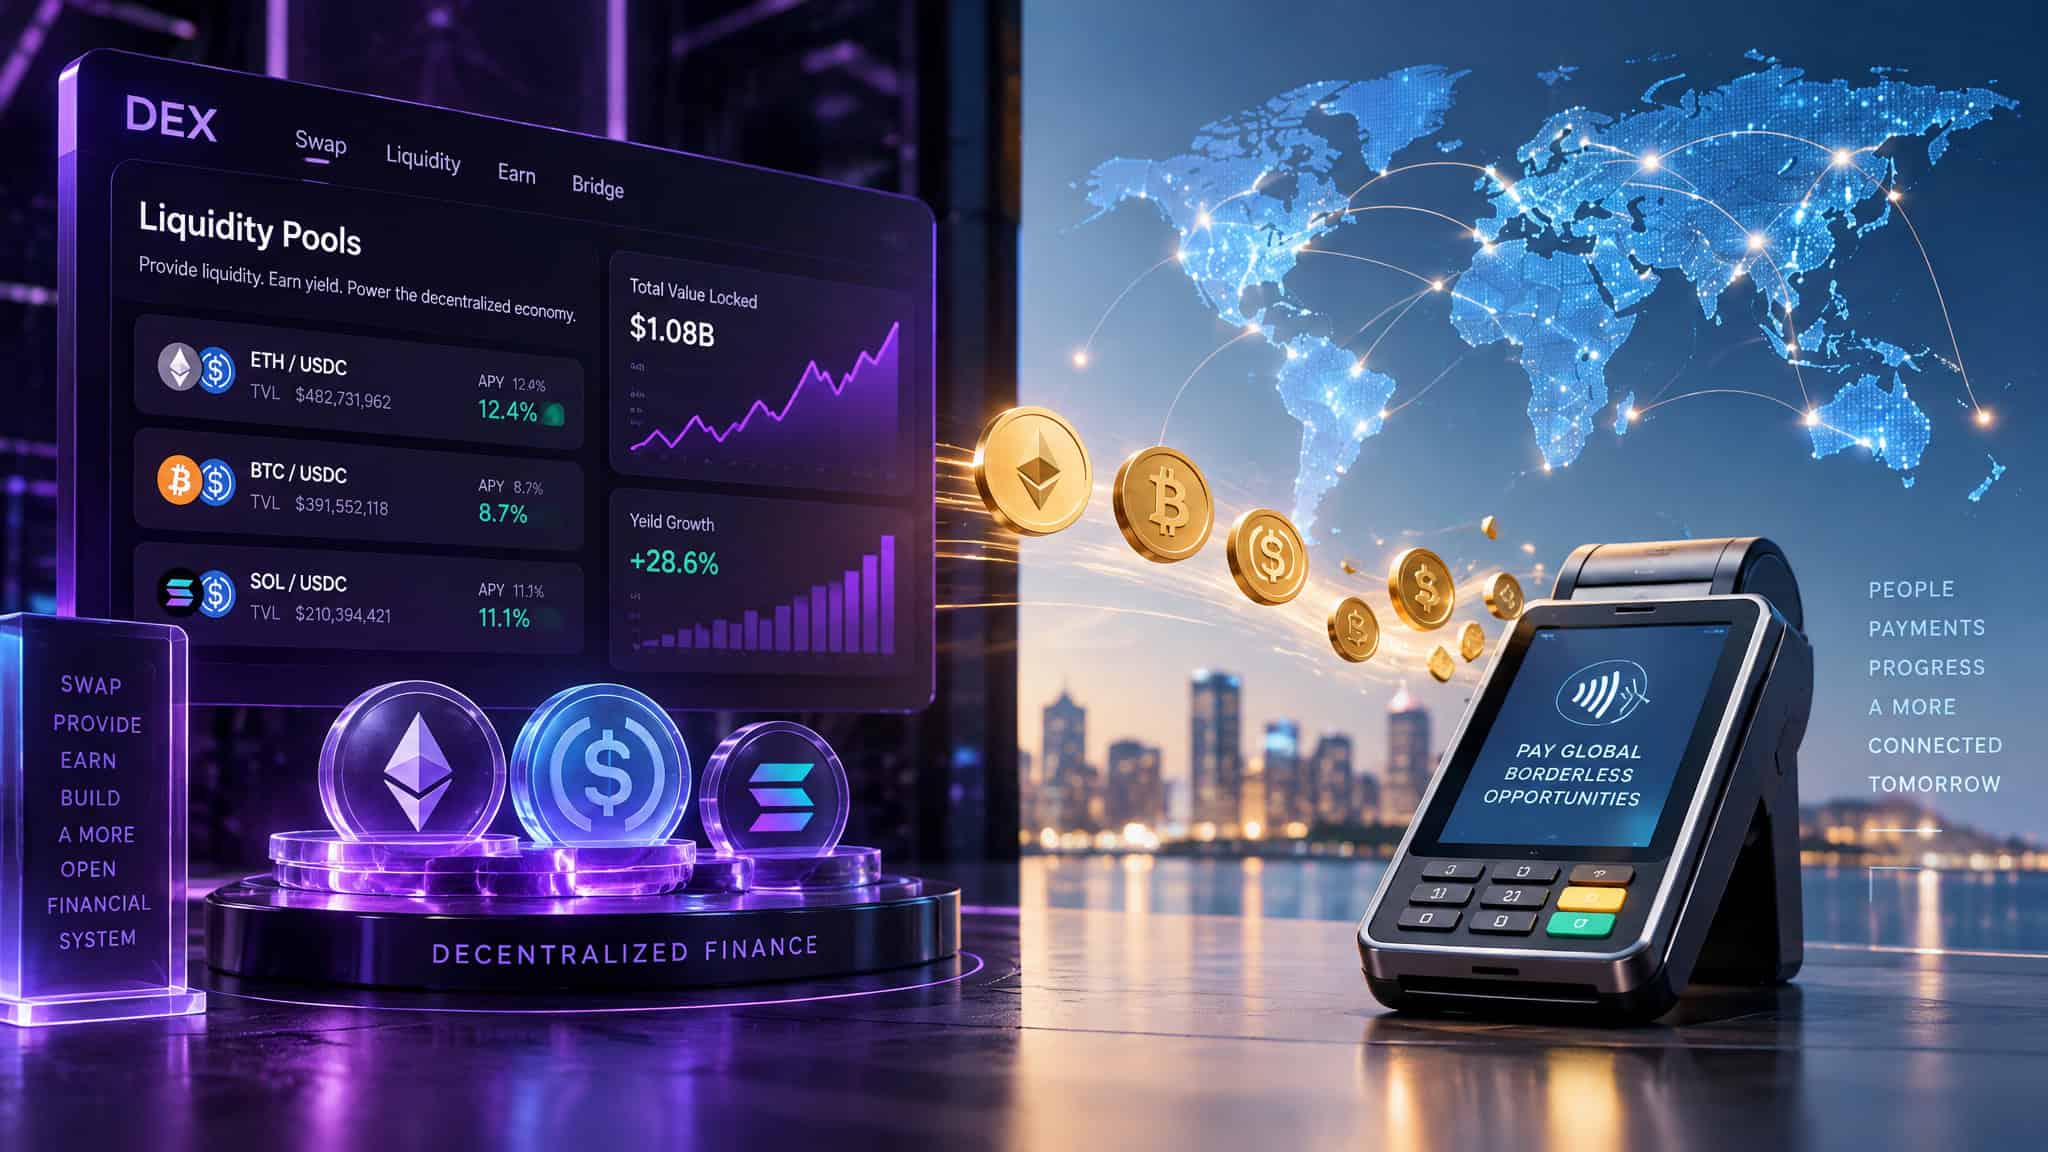
Altcoins do the other half of the division of labor. They bootstrap DeFi liquidity through yield farming, incentivize user participation, and govern protocols. On proof-of-stake chains, validators stake the native token to process transactions, which means the token is also the security budget.
One fun Q2 outlier: prediction-market activity rose 48.7% to $113.8 billion, driven by sports betting around the World Cup, NBA Finals, and Wimbledon. A concrete cause for the only sector that grew while everything shrank.
Risk comparison: what can go wrong with each
Altcoin risk is continuous price exposure; stablecoin risk is binary tail events.
On the altcoin side, prices swing on sentiment, regulatory news, and tech shifts, and because anyone can deploy a smart contract, anyone can deploy a smart contract, so the market is crowded with projects of varying quality; vet contract security and roadmap viability before buying in. Altcoins swing as hard as Bitcoin, producing six- or seven-figure returns or near-zero wealth. One source puts it vividly, calling holding altcoins a constant game of russian roulette; that’s their framing, not mine. The grounded version is the dogecoin millionaires episode: in the early-2021 boom, some holders hit six or seven figures.
Sellers exited with those gains intact. Non-sellers fell back to almost nothing. Both halves together or the story lies.
On the stablecoin side, the main risk is de-pegging, losing parity with the tracked asset when the market loses confidence in the reserves.Broken contract logic or failed offchain reserves can break the peg and torch trust. Fiat-backed coins also carry custodian counterparty risk: your dollar exists, but someone else is holding it. Institutions mitigate by demanding real-time reserve transparency, a practice worth copying.
And the no-safety-net facts, delivered straight: crypto can become illiquid at any time, suits only high-risk-tolerance investors, and is more susceptible to manipulation than securities. It’s not FDIC or SIPC insured, not a bank obligation, and carries none of the protections of registered securities.
What the 2026 market data shows: neither class is a monolith
Crypto lost over $300 billion in Q2 2026, down 12.6% from $2.4 trillion to $2.1 trillion, a third consecutive quarterly decline that ended June at its lowest level since September 2024, about 52% below the October 2025 peak. Bitcoin fell about 14%, Ethereum more than 25%, despite positive U.S. stock performance. Average daily volume fell nearly 21%, and centralized-exchange volume dropped about 28% to $1.9 trillion. The attributed causes are several inputs, not one: rising ETF withdrawals, a hawkish Federal Reserve, shifting U.S..Iran tensions, and Strategy’s partial Bitcoin sale.
Issuer divergence
Inside the “stable” category, the two giants moved opposite directions. USDC lost $3.7 billion to end Q2 at $73.5 billion, the largest stablecoin decline, while USDT gained about $300 million to reach $184.4 billion in the same quarter. Zooming to the newer issuers: RLUSD up 86% YTD versus PYUSD down 22% YTD, roughly $1.5 billion lost from its March 5 peak.Per DefiLlama’s past-week flows, RLUSD added $112 million while PYUSD shed $61 million.
Chain-level flows
PYUSD’s weekly drop was mostly one chain: Arbitrum, where supply fell from $320 million to $229 million. RLUSD’s story is a chain-share flip: XRPL’s share fell from 58.9% to about 43-44% while Ethereum rose to about 56%, then the Sept. 21-28 week reversed it, with XRPL growing $63 million versus Ethereum’s $49 million. The report labels that rebound possibly temporary, and I’m preserving the hedge rather than turning a wobble into a verdict.
Then there’s the macro inversion, stated plainly and left sitting: dollar tokens keep growing faster than the coins they’re used to trade. XRP near $1.49, down about 19%, despite XRPL growth. BTC near $83,000, about 5% below its Jan. 1 open, even after a 44% Q3 rally, which implies the rally started from an intra-quarter low; a big rally can still leave you net down. All observed, and one quarter’s flows are not a permanent issuer ranking.So both labels cover internally messy categories, and the observed activity is migrating to the stablecoin layer.
Which fits your needs: payments versus growth
Stablecoins are lower-volatility, not risk-free. That’s the honest answer to the safer-question version of this choice: lower volatility but non-zero issuer risk, exactly what the USDC/USDT and RLUSD/PYUSD divergences above show. Stability of value is not absence of issuer risk.
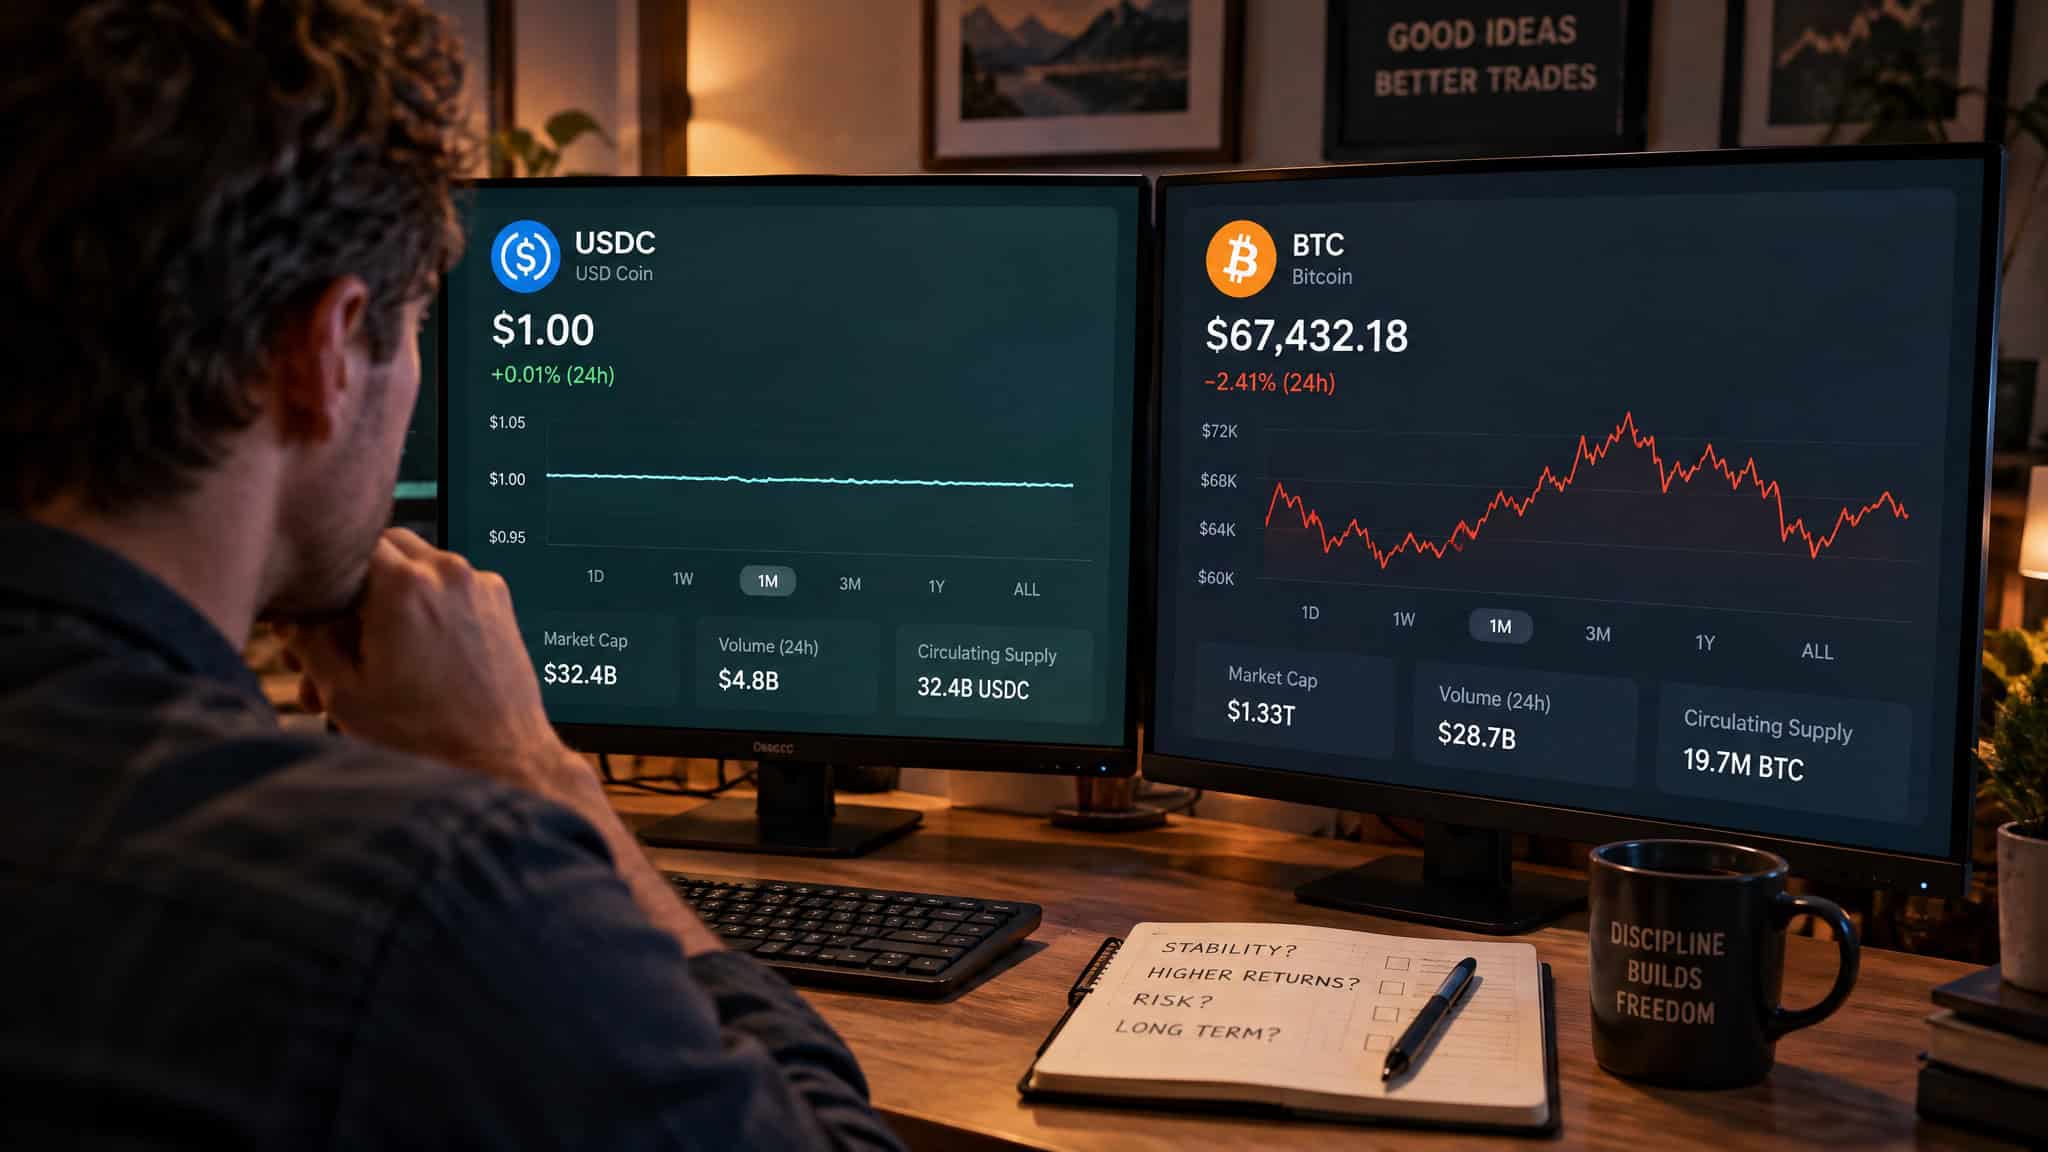
Think division of labor, not either/or. Stablecoins for capital preservation, settlement, and value transfer; altcoins for capital appreciation and DeFi participation. If your job is moving money, remittances, payroll, settlement, the stablecoin case is straightforward, and it’s why they’re the bridge between traditional finance and the onchain world.
For choosing a specific stablecoin, the sources support criteria rather than step-by-step buying instructions, so here’s what to check: the backing model, reserve transparency, and which chains the token actually circulates on. In practice, people often pick by brand familiarity and never check chain distribution, a gap that matters when supply migrates, as PYUSD’s Arbitrum drop and RLUSD’s XRPL/Ethereum share shift both showed this year. A typical setup: pick the peg you trust, verify the receipts, then check where the token actually lives.
Complementary roles: what each class does the other can’t
The split is simple: altcoins handle growth, governance, and network security; stablecoins handle payments and settlement, boring on purpose, and that’s the compliment.Both sit on the same oracle infrastructure. Together they could scale to institutional finance and next-generation dApps, could, not will. The macro observation still stands: dollar tokens keep growing faster than the coins they trade.
Frequently Asked Questions
Why are banks against stablecoin?
Stablecoins compete with traditional banking rails by enabling instant settlement without going through banks, which is why major financial institutions are both exploring the technology and watching it warily. Fiat-backed coins also shift the trust question onto issuers: your dollar exists, but someone else is holding it, and banks are the incumbent custodians of that role. The honest framing is that stablecoins are becoming the credit asset themselves, not just cash equivalents — a direct challenge to existing intermediaries.
What’s the difference between stablecoins and altcoins?
One variable: volatility. Altcoins are every cryptocurrency built to ride price movement and network adoption, while stablecoins are engineered to erase that movement and hold steady near a fixed value like $1.00. Altcoins suit traders and DeFi participants; stablecoins suit anyone moving value who doesn’t want a price bet.
Is Bitcoin an altcoin?
No — Bitcoin is excluded from the altcoin category by definition. Altcoins are any cryptocurrency other than Bitcoin, because Bitcoin is the reference point the entire category is defined against. It’s the baseline, not a member.
Are stablecoins safer than altcoins?
Lower volatility, yes — but not risk-free. Stablecoin risk is binary tail events like de-pegging and custodian failure, while altcoin risk is continuous price exposure that can produce massive returns or near-zero wealth. Stability of value is not absence of issuer risk, and crypto in general isn’t FDIC or SIPC insured and carries none of the protections of registered securities.
