If you’ve been running software teams since 2022, you’ve watched a genuinely annoying piece of the tax code grind your deductions into powder. The Tax Cuts and Jobs Act forced companies to capitalize research costs, spreading a deduction that used to land in one year across five years domestically and fifteen years offshore. For a dev shop paying real engineer salaries, that meant the money you spent writing code this year barely touched this year’s tax bill.
OBBBA fixed it. Mostly.
The One Big Beautiful Bill Act created Section 174A, which permanently restores full expensing of domestic research and experimental costs for tax years beginning after Dec. 31, 2024. Your 2025 domestic developer wages? Fully deductible, calendar-year filers, on the return you’re prepping right now. But foreign costs still amortize over 15 years, unchanged from the TCJA era, and the fine print is where this stops being simple.
So I dug into the actual mechanics: which election applies, what happened to the 2022-2024 costs stuck on your books, and where the obvious answer turns out to be the expensive one. Here’s the map.
Key Takeaways
Domestic software development costs are fully deductible again under Section 174A for tax years starting after Dec. 31, 2024, and the change is permanent with no sunset clause; foreign software development still amortizes over 15 years, unchanged.
Three accounting paths exist for 2025 and later: immediate expensing under 174A(a), a sticky 60-month capitalization election under 174A(c), or an annual 10-year ratable deduction under Section 59(e), and for leveraged companies the amortization route can produce a higher business interest limitation.
Unamortized domestic R&E from 2022-2024 can be deducted in full on the 2025 return, split ratably over 2025 and 2026, or left on the old five-year schedule, and small businesses with $31 million or less in average annual gross receipts could retroactively amend 2022-2024 returns.
Table of Contents
What changed: from TCJA capitalization back to Section 174A expensing
TCJA (that’s P.L. 115-97, signed in 2017) required specified research and experimental expenditures in tax years beginning after Dec. 31, 2021 to be capitalized: five years of amortization for domestic research, fifteen for foreign. OBBBA reversed the domestic half. New Section 174A permanently allows full expensing of domestic R&E expenditures paid or incurred in tax years beginning after Dec. 31, 2024. Permanently is the operative word here. No sunset clause, no “review in five years,” just a clean revert of a bad commit.
The practical payoff for calendar-year filers: the domestic R&E you spent during 2025, including your engineers’ salaries, is deductible in full on the 2025 return.
And the old rule wasn’t just annoying, it was measurably harmful. Stanford Business School research, cited via the Tax Foundation, found the capitalization era cut R&D investment by $12.1 billion and raised effective tax rates by 62 percent. The intuition isn’t hard: a deduction deferred five years loses real value to inflation and the time value of money. One illustrative figure from that analysis: $1,000 of equipment depreciated over six years loses about 18 percent of its real deduction value at 3 percent inflation and a 3 percent discount rate, raising after-tax cost roughly 3.8 percent for a corporation at the 21 percent rate. Multiply that by an entire R&D budget and you get the damage the study measured.
So this isn’t a giveaway. It’s a measured reversal of a policy that, empirically, made companies invest less in the thing the policy supposedly wanted to encourage.
Are software development costs capitalized or expensed under OBBBA?
Software development remains an R&E expenditure under Section 174(c)(3) and the new Section 174A(d)(3), so domestic software development costs are fully expensable for tax years beginning after Dec. 31, 2024, while foreign software development costs still get capitalized and amortized over 15 years. Your code counts. The classification question is settled, for good.
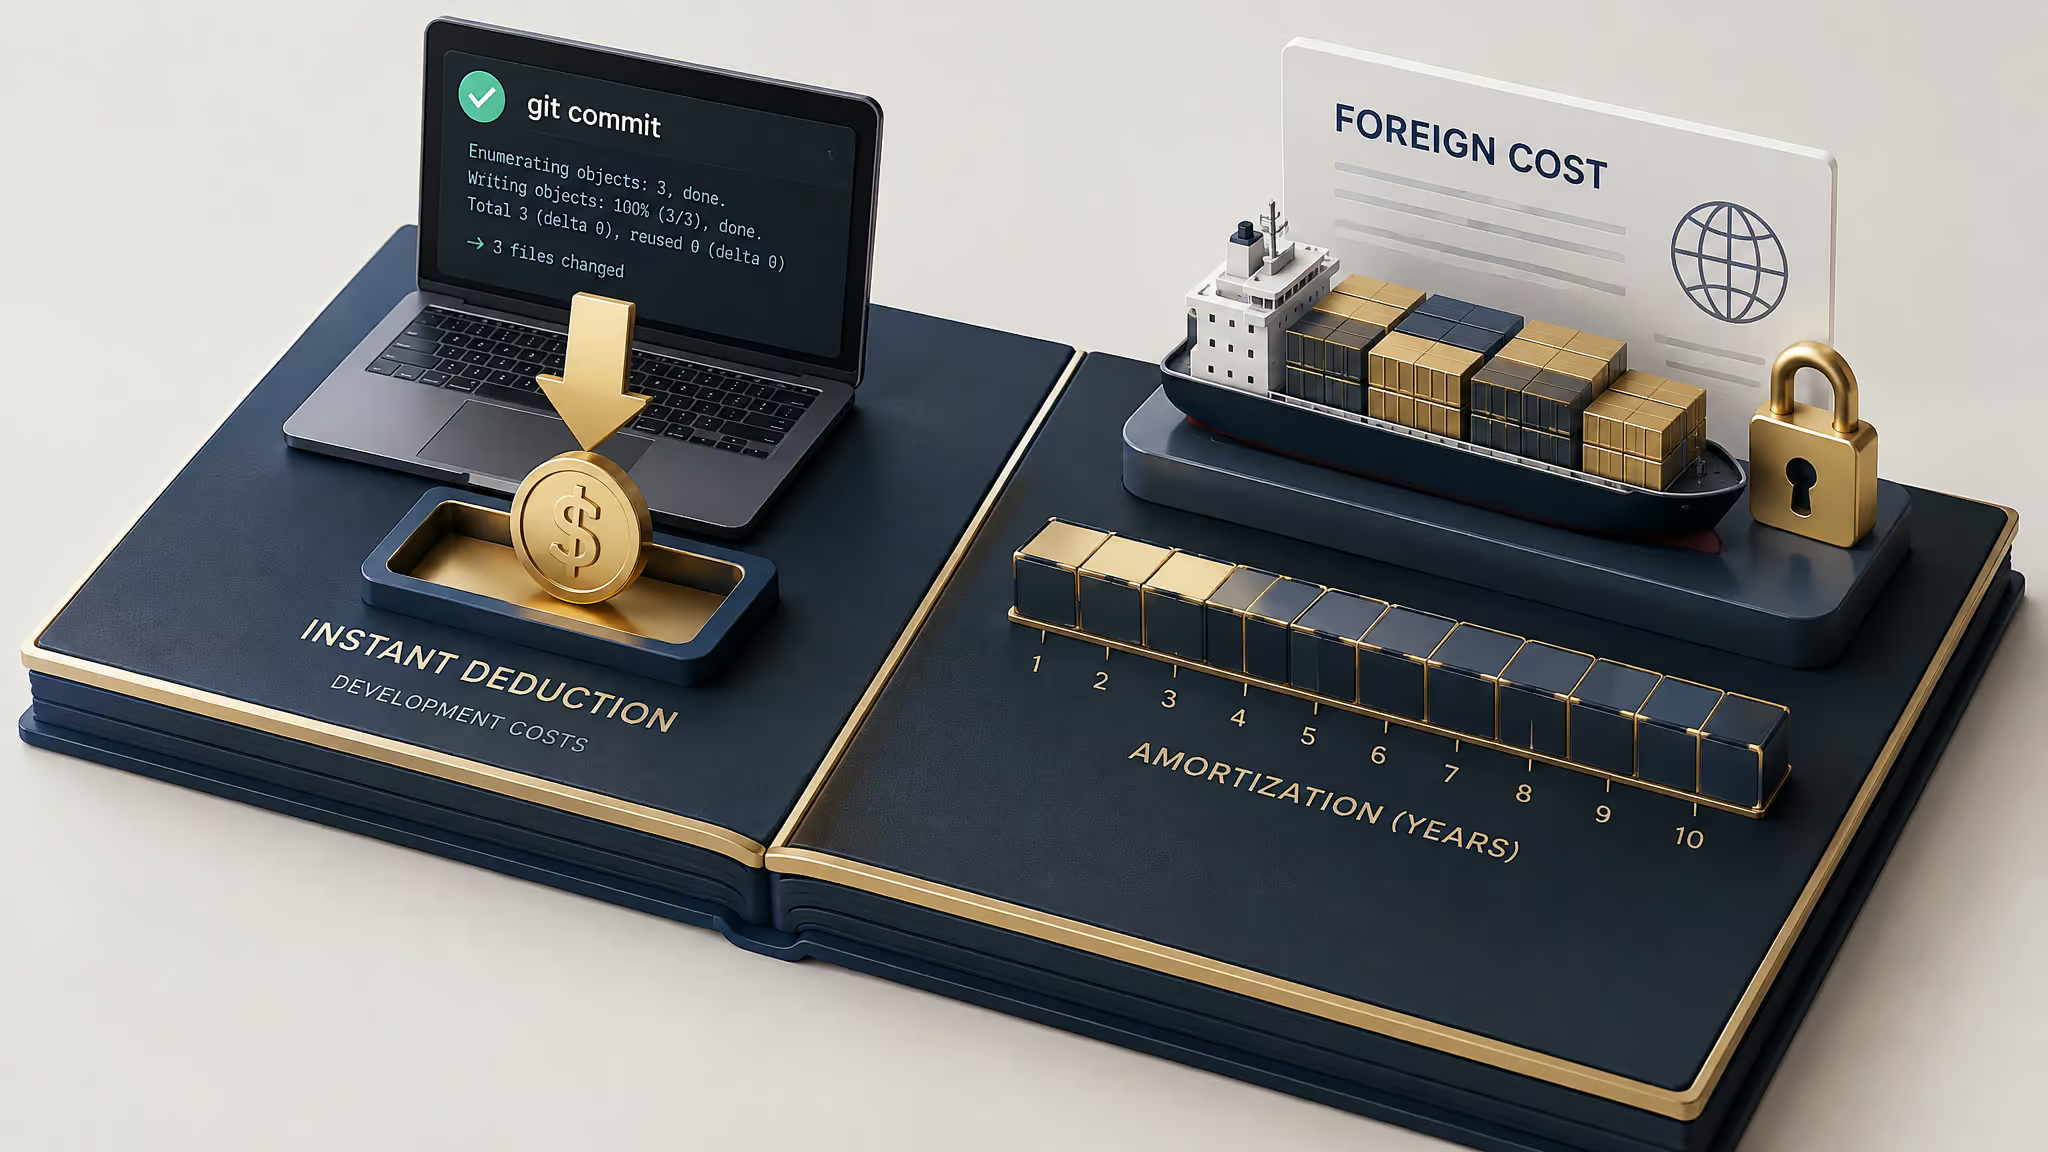
While we’re killing misconceptions: no, software isn’t “depreciated over 3 or 5 years” in this context. Developed software follows Section 174/174A, not depreciation schedules, unless the costs are chargeable to depreciable property, which is carved out of expensing. There’s no flat 3-or-5 answer; the R&E classification is the whole game.
The old safe harbor is dead
Here’s the consequence most general alerts never spell out. Because 174A(d)(3) now classifies software development as R&E, Section 5 of Rev. Proc. 2000-50 is effectively obsolete for software development costs in tax years beginning after Dec. 31, 2021. That’s a 25-year-old guidance document getting formally retired, and it matters because plenty of companies built their 2022-2024 software cost treatment on that safe harbor. If your historical treatment leaned on it, the ground has moved underneath you.
The operative definition lives in interim guidance
Here’s the part I had to read three times: the IRS never issued regulations defining software development under TCJA Section 174. What we got instead was interim guidance in Notice 2023-63, clarified and modified by Notice 2024-12, describing which activities count as software development for Section 174(c)(3). And no new Section 174A(d) software guidance exists yet. So the map you’ve got is the map: align your software-development identification with Notices 2023-63 and 2024-12, because that’s the operative definition right now.
This is where the documentation thread starts, and it’s load-bearing. A common pattern practitioners describe: companies tracked R&D carefully for credit purposes but never mapped which engineering activities count as software development under the notices. Then when it’s time to quantify the domestic/foreign split, the general ledger, payroll records, and project-tracking systems don’t reconcile to the activity definitions at all. If that’s you, the fix is reconciliation work, and it needs to happen before the return is filed, not during an audit.
Which software development costs qualify?
Qualifying costs include wages of engineers, scientists, and software developers; supplies and materials consumed in research; contractor payments at 100 percent of the total contract amount (no haircut, which is genuinely generous); and laboratory equipment and facilities costs subject to standard capitalization rules. Mostly, this means your payroll and your contractor invoices.
What’s out:
- Foreign research of any kind
- Costs capitalized as depreciable property
- Survey or feasibility studies
- Routine quality control testing
The test underneath all of it: the activity has to constitute research or experimentation intended to discover information that eliminates uncertainty about developing or improving a product, process, or formula. Uncertainty is the magic word. If your team is figuring out whether something can be built and how, that’s R&E, and those efforts translate into qualified research expenses like wages, supplies, and contract research. If it’s routine maintenance or QA, it isn’t.
Before you quantify anything, classify your cost lines against this list. Software development still counts as an R&E expenditure under Section 174(c)(3) and new Section 174A(d)(3), so domestic costs are deductible while foreign ones stay capitalized over 15 years, it’s the foundation for everything downstream.
Choosing among the three accounting alternatives
Section 174A gives domestic R&E three accounting paths, and which one fits depends less on ideology than on your interest expense, income trajectory, and entity structure. The default is immediate deduction under Section 174A(a): deduct domestic R&E expenditures paid or incurred during the taxable year, full stop. Option two is the Section 174A(c) election to capitalize (except amounts chargeable to depreciable property) and amortize ratably over at least 60 months starting with the month you choose; it’s due by the federal return due date including extensions, and it applies to the election year and all future years unless you receive consent to change. Option three is the conforming Section 59(e) election to deduct domestic R&E ratably over 10 years starting with the year you spent it, and unlike 174A(c), it’s an annual choice you make fresh each year.
Quick test: Leveraged with serious interest expense? Run the 163(j) math on amortization before defaulting to expensing — the slower deduction can buy more interest room.
When expensing is the wrong default
Here’s the part I find honestly kind of elegant. Beginning in 2025, amortization deductions get added back when computing adjusted taxable income under Section 163(j), the business interest limitation. That means electing capitalization and amortization produces a higher business interest limitation than immediate expensing. For a leveraged company carrying serious interest expense, the slower deduction buys more room to deduct interest. The “expense everything” consensus inverts.
Other cases where the flashy default underperforms: expensing in a loss year feeds an NOL that’s capped at 80 percent of future taxable income, so deductions you can’t use are just spreadsheet decoration. Percentage-of-completion method users may forgo expensing. And if you’re a partner or shareholder getting a K-1 from a flow-through with significant domestic R&E, note that for AMT purposes individuals must capitalize R&E that’s deductible for regular tax and amortize over 10 years. Two ledgers, one wallet.
The composite failure mode practitioners describe: a team defaults to expensing, then discovers the NOL or 163(j) problem during modeling, after which the analysis has to happen anyway, just more urgently. Run the modeling before the return is filed.
The permanence tradeoff
The flip side of “expense everything” is that taxpayers expecting considerable future income may deliberately elect capitalization under 174A(c) or 59(e) to match deductions against that income instead of burning them in a low-income year. Deductions are worth more when your rate is higher. And Rev. Proc. 2025-28 confirms that the unamortized domestic R&E deduction counts as amortization for 163(j) purposes, so the add-back mechanic holds across the transition options too.
Think of the 174A(c) election like a config file you can’t easily revert. The 59(e) election is the flag you pass per-build. Pick accordingly.
Foreign software development: the 15-year rule that didn’t change
- Foreign software development costs: still mandatory capitalization and amortization over 15 years under OBBBA, unchanged from TCJA Section 174. Foreign R&E is excluded from the new expensing rules.
- Domestic software development costs: under new Section 174A, taxpayers may immediately deduct domestic R&E expenditures paid or incurred during the taxable year.
- Split onshore/offshore teams: only the domestic side gets the expensing treatment; the foreign side stays on the 15-year schedule.
And the fine print is worse than the headline. Section 174(d) prohibits immediate recovery of unamortized foreign R&E basis upon disposition, retirement, or abandonment. The stuck basis stays stuck. For events after May 12, 2025, there’s an extra twist: you also can’t reduce the amount realized on disposition.
So you can’t even claw back partial value through the sale price. Foreign basis is genuinely locked.
The strategic implication is observation, not advice, but it’s real: the domestic/foreign split is now a genuine staffing decision. Companies with offshore developers may re-evaluate their outsourcing math given the friendlier U.S. treatment, shift work onshore, or engage U.S.-based contract researchers to qualify for full expensing. Multinationals with foreign research teams face the same calculus. The tax code is quietly shaping org charts, which is exactly the kind of thing that sounds like a conspiracy theory until you read the statute.
Recovering unamortized 2022-2024 costs
Taxpayers can deduct unamortized 2022-2024 domestic R&E by electing accelerated recovery, and here’s how the options work. The transition rules offer three paths for the basis sitting on your books from tax years beginning after Dec. 31, 2021 and before Jan. 1, 2025: deduct all remaining unamortized amounts in the first tax year beginning after Dec. 31, 2024 (your 2025 return, a lump-sum unlock), split the amount ratably over two years such as 2025 and 2026, or keep amortizing over the remaining five-year schedule. That last one is rarely sensible given the time value of money, but it’s the do-nothing default. And the accelerated recovery is optional; nobody’s forcing the lump sum.
Method-change mechanics
Applying 174A is a change in method of accounting on a cut-off basis for amounts paid or incurred in tax years beginning after Dec. 31, 2024. New rules apply going forward; old basis stays put. One niche-but-real edge case: taxpayers with a short taxable year beginning after Dec. 31, 2024 and ending before July 4, 2025 must use a modified cut-off approach with a Section 481(a) adjustment covering only the unamortized domestic R&E from the short year. Fiscal-year filers and anyone whose year got shortened by an M&A transaction, this one’s yours.
Model the two elections as one decision
The 2025 treatment election and the catch-up recovery election are independent checkboxes, but they stack. A full catch-up deduction plus immediate expensing of 2025 costs can generate an NOL that’s 80 percent trapped against future income, and the 163(j) and AMT effects layer on top. Model both together, interest limitation, NOL, and AMT consequences included, before making either election.
R&D credit interactions: Section 41, 280C(c), and Form 6765
OBBBA restored the pre-TCJA Section 280C(c) tradeoff: for tax years beginning after Dec. 31, 2024, claiming the gross research credit requires reducing your domestic R&E expenditures by the credit amount, unless you elect the reduced credit instead, which is cut by the maximum 21 percent corporate rate and must be elected on a timely filed return including extensions. The credit and the deduction tug on each other; you can’t max both.
Then there’s the two-word statutory edit with outsized effects. Section 41(d) changed “may be treated” to “are treated” as 174A domestic R&E expenditures for qualified research expenditure status. Optional became mandatory, which means qualified research expenditures must now trace to costs actually classified as 174A expenditures. That may require distinct Form 6765 reporting even though the same costs are immediately deductible, and the revised, significantly extended form makes R&D tax a year-end planning item rather than an April afterthought.
The failure mode to know about: claiming the R&D credit on amended returns gets messy if the costs weren’t originally classified as 174A expenditures, because reclassification usually requires an accounting method change, which isn’t allowed on amended returns. You can’t just relabel it later. Get the classification right the first time.
One historical wrinkle worth knowing: TCJA capitalization accidentally disabled the 280C(c) reduction, making R&D credits captured in 2022, 2023, and 2024 worth about 21 percent more. A glitch that paid. OBBBA quietly claws that back for years after Dec. 31, 2024.
Small business retroactive relief: the $31 million path and its catch
Yes, small businesses with average annual gross receipts of $31 million or less could amend their 2022-2024 returns to apply Section 174A retroactively. The Section 448(c) test uses average annual gross receipts of $31 million or less (one source rounds to roughly $30 million; $31 million is the 2025 figure), computed for the first tax year beginning after Dec. 31, 2024 and measured over 2022-2024. Two doors: amend the returns for each affected year, or file a change in method of accounting. Tax shelters allocating 35 percent or more of losses to limited partners or limited entrepreneurs in 2025 are ineligible.
But there’s a deadline to watch. Amended returns must be filed by the earlier of July 6, 2026 or three years from the return’s filing date. There’s even a calendar quirk: the statutory July 4, 2026 falls on a Saturday, making Monday July 6 the operative date. And the 280C(c) catch still applies, retroactive 174A application drags the reduced-credit election along with it, so the net-effect math matters for anyone still qualifying.
The catch that came with the good news: retroactive application of 174A forced retroactive application of the 280C(c) amendments too, including making or revoking the reduced-credit election on originally filed returns. OBBBA temporarily allowed the reduced-credit election on amended returns (normally it’s original-only), but it had to be elected by July 6, 2026, and it cost roughly 21 percent of claimed credits. So the tradeoff was real: accept a substantial credit cut to preserve full deductions, and the extra pre-tax deduction may be partly offset by the reduction. Net effect, not gross effect, is what mattered. The “free money” assumption broke down the moment you did the math honestly.
Partnership, state, and timing considerations
States do not uniformly conform to 174A expensing; whether you get the state-level benefit depends on which version of Section 174 your state follows, and the map splits into three tiers. That’s the headline for this whole cluster of issues, and each piece deserves its own look.
Partnership mechanics
If you’re in a partnership, the elections play out at the partner level, and the filing route is specific. Eligible BBA partnerships must make the small-business OBBBA election on an AAR under Rev. Proc. 2025-28, unless they file a change in method of accounting instead. That’s a genuine departure from prior IRS practice, like the TCJA bonus depreciation regulations, which allowed BBA partnerships to file amended returns. New playbook, worth noting.
The mechanics push additional deductions out to reviewed-year partners, with tax effects landing on each partner’s return for the year the AAR is filed, 2025 or 2026. Timing matters here: when the AAR gets filed affects whether partners actually realize the benefits, so run the numbers with your partners before filing, not after. Two more partner-level realities: partner-level limitations may block partners from using their distributive share of any accelerated deduction (the deduction can exist on paper and still not help you), and tax distributions made on 2025 estimates may not reflect what the OBBBA elections actually do. The estimate and the reality can drift.
State conformity
Three buckets, and knowing yours changes everything:
- Illinois and New York conform to new Section 174A. Good news if you’re there.
- About a third of states, Florida and North Carolina included, still conform to TCJA Section 174. Federal expensing, state amortization. A big chunk of the map didn’t move.
- California conforms to pre-TCJA Section 174, which actually allows full expensing of domestic and foreign R&E. The counterintuitive anomaly: the state everyone loves to complain about has the friendliest foreign treatment.
Field note: California still allows full expensing of domestic and foreign R&E under pre-TCJA Section 174, while a third of states still follow TCJA amortization.
Several states let you elect which version of Section 174, or possibly 174A, applies, and whether federal elections are recognized in decoupled states is an open question. Some states were expected to change policies before the 2025 filing season via special or general legislative sessions, with state regulatory guidance expected in coming months. The map was still being drawn at last word. The key practical check: figure out whether elections like 174A(c) capitalization are even available at the state level when not made federally. The federal-optimal election can be actively wrong for the state return, which makes state conformity a modeling input, not an afterthought.
Rev. Proc. 2025-28 and the calendar
The IRS released Rev. Proc. 2025-28 on Aug. 28, 2025 as the procedural how-to for implementing 174A and its elections. It clarified that the deduction of unamortized domestic R&E counts as amortization for federal income tax purposes, including for 163(j), but open items remain: the character of released deductions (R&E expense versus amortization), per-project capitalization elections, treatment of unfiled 2024 returns, and the interaction between AARs and amended returns. Still figuring this out, without drama.
On timing: timely analysis may enable reduced Q3 estimated payments, and the guidance’s impact belongs in the next quarterly income tax provision, Q3 for calendar-year filers. Real cash, this quarter. And if you’re on extension for your 2024 business returns, the extended deadline of Sept. 15, 2026 is days away. Don’t file on autopilot; resolve the elections with an advisor first.
The documentation thread comes home here too. Reconcile your general ledger data, payroll records, and project-tracking systems to quantify the domestic/foreign split, and keep the documentation for audit defense. Your project tracker just became a tax document. (If you want the fundamentals of how software costs landed in this situation in the first place, the earlier piece on whether software development is tax deductible covers the pre-OBBBA landscape, and our guide to the R&D tax credit for software development digs into the Section 41 side that couples with all of this.)
One more cost-recovery note while we’re here: R&E expensing isn’t the only goodie in the bill. 100 percent bonus depreciation is permanently extended for property placed in service after Jan. 19, 2025 (new hardware, full write-off). Section 179’s expensing limit went from $1 million to $2.5 million, with the phaseout up to $4 million. And there’s a temporary Section 168(n) expensing window for manufacturing structures where construction must begin after Jan. 19, 2025 and before Jan. 1, 2029, with the property placed in service by Jan. 1, 2031. The Tax Foundation modeled permanent domestic R&D expensing at +0.10 percent long-run GDP (about $178 billion in revenue cost), permanent bonus depreciation at +0.60 percent GDP, and manufacturing property expensing at roughly zero GDP effect.
Expensing delivers the most growth for the least cost among the bill’s provisions. Straight numbers, make of them what you will.
The one-pass sequence
If you take one thing from this, make it the order of operations: classify your costs against the software-development definition in Notices 2023-63 and 2024-12, quantify the domestic/foreign split, model all three accounting alternatives together with the 163(j), NOL, and AMT effects, then layer in the catch-up election, the credit election, and the state overlay, with documentation reconciled before any of it hits a return. The analysis has to run before the return is filed, because the 174A(c) election is effectively permanent while 59(e) and the catch-up are more reversible. Most of the small-business retroactive window closed with the July 6, 2026 deadline, and open items like the character of released deductions and per-project capitalization elections are still awaiting IRS guidance. Keep the config updated: as the rules evolve past 2025, your processes, documentation, and planning deserve a recheck, because in tax code as in software, the migration path is only as good as your last deployment.
Frequently Asked Questions
How do I deduct unamortized Section 174 costs from 2022 to 2024 after OBBBA?
You have three paths for the basis sitting on your books: deduct all remaining unamortized domestic amounts in full on your 2025 return, split them ratably over 2025 and 2026, or keep amortizing over the remaining five-year schedule. The lump-sum unlock is optional, and the do-nothing five-year default is rarely sensible given the time value of money. Small businesses with $31 million or less in average annual gross receipts could also amend 2022-2024 returns, but that window closed July 6, 2026.
How does the R&D tax credit interact with Section 174A expensing under OBBBA?
OBBBA restored the pre-TCJA Section 280C(c) tradeoff: claiming the gross research credit reduces your domestic R&E deduction by the credit amount, unless you elect the reduced credit (cut by the 21 percent maximum corporate rate) on a timely filed return including extensions. Section 41(d) also changed ‘may be treated’ to ‘are treated’ as 174A expenditures, so qualified research expenditures must now trace to costs actually classified as 174A expenditures — and reclassification later usually requires an accounting method change, which isn’t allowed on amended returns.
