We went looking for free finance tools expecting the usual landfill of sign-up walls and “premium” upsells, and instead found something good: the actual Securities and Exchange Commission, the regulators themselves, shipping a full toolkit of financial planning tools at no cost, no account required, and even an AI financial planner that asks no questions before it starts answering yours. That discovery sent us down a rabbit hole, and the view from inside is worth sharing.
Here’s the organizing idea: every financial planning tool exists to execute a specific technique. So the useful question isn’t “which app is best,” it’s “which technique am I trying to run.” Tools range from apps and calculators to spreadsheets and printed worksheets. Techniques span budgeting, debt payoff, retirement, tax, investing, insurance, and estate planning. Below: the SEC’s free toolkit, the consumer apps worth your time, the core techniques, the math underneath all of it, the retirement lifecycle, and exactly where free tools stop being the right answer.
Key Takeaways
Investor.gov, the SEC’s free site, bundles five tools (Fund Analyzer, Retirement Ballpark E$timate, Social Security Retirement Estimator, EDGAR, a background checker) and four calculators, all free with no signup.
The math matters: on a $350,000, 30-year, 6% mortgage, an extra $500 per month cuts payoff from 360 to 224 months and saves over $170,000.
Free tools break down when you need Roth conversions, tax-loss harvesting, withdrawal sequencing, or help modeling a job change, an inheritance, a divorce, or a new business, that’s fiduciary advisor territory.
Table of Contents
| Exact model | Decisive documented advantage |
|---|---|
| Investor.gov | Free SEC-run investor education site with calculators, alerts, and audience-specific resources on a secure .gov domain |
| Debt Payoff Planner | Free app that generates a payoff plan with visuals of payoff timeline, interest paid, and required payments |
| The Tools & Techniques of Financial Planning (14th Edition) | Professional reference spanning budgeting, credit/debt, education funding, retirement, tax, investment, risk management, and estate planning |
Model details below derive from the cited sources; check the brand pages for current pricing.
Observed prices
Observed prices run $600, $6,000 across 1 source (checked Tuesday, September 15, 2026). Sources: thrivent.com.
Investor.gov: the SEC’s free financial planning tools
Investor.gov is the SEC’s free toolkit of financial planning tools, and it rules. No signup, no cost, run by the people who regulate the markets. What’s in the drawer:
- Fund Analyzer shows what fees actually cost you over time across mutual funds, exchange-traded funds and notes, and money market funds. Fees compound like returns, in reverse, so the number you’ll actually pay beats the sticker expense ratio.
- Retirement Ballpark E$timate and the Social Security Retirement Estimator pair as a first-pass retirement gap check. The Social Security one uses your real earnings record to produce a personalized benefit estimate, and it’s free.
- EDGAR is the cool find if you like going to the source: searchable public filings from companies, mutual funds, ETFs, and some annuities.
- Investment Professional Background Check is the run-it-before-you-hand-anyone-money utility. You can check any professional’s credentials and regulatory standing before you hand over money.
The four calculators cover compound interest (go change the sliders and watch), savings goal (it reverse-engineers your monthly number), required minimum distributions by age, and college savings. Trust aside: it’s hosted on a secure government domain, and MyMoney.gov sits linked in the footer.
Free budgeting apps, worksheets, and templates
Legitimate free budget templates exist, and you don’t have to start from a blank grid. Consumer.gov has a free worksheet where you enter income and expenses and instantly see a red number or a surplus. The nonprofit American Consumer Credit Counseling (ACCC) offers a free printable worksheet, an analog-on-purpose way to start. And there are free Excel and Google Sheets templates from sources like Canva.
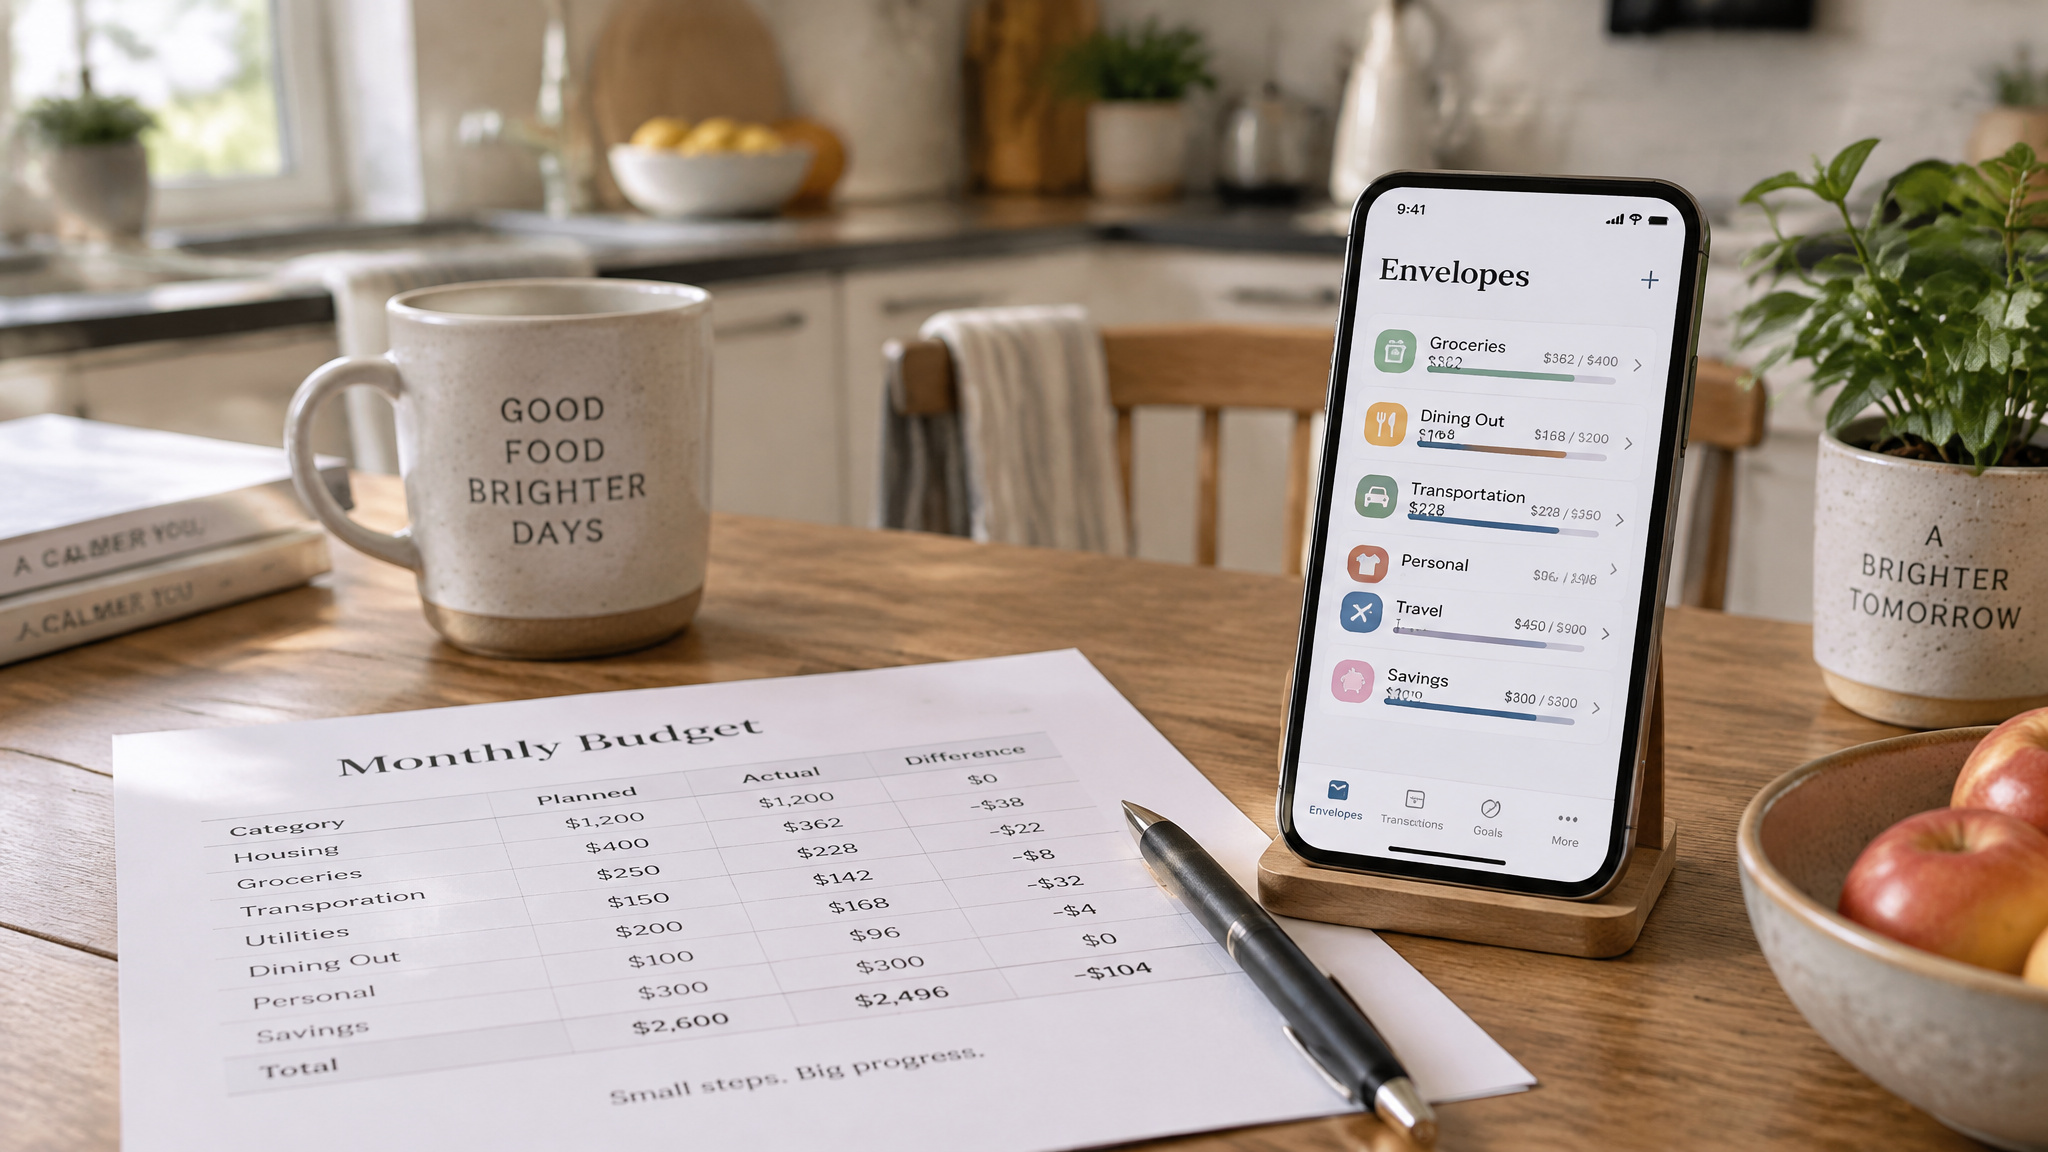
On the app side, Goodbudget runs the envelope system (you divvy up cash for rent, groceries, dining out into digital envelopes), and the free tier gets you exactly 10 regular plus 10 additional envelopes on 2 devices, handy for a shared household budget. MoLo is the surprise find: free, ad-free, syncs your bank and card accounts, auto-categorizes transactions, predicts paydays and recurring bills, and estimates what’s left at month’s end. SmartAsset runs a calculator buffet: investment return, retirement, income tax, take-home pay, plus advisor matching and a cost-of-living relocation calculator. Bank of America’s Erica chatbot reviews spending and flags duplicate charges and merchant refunds.
The real choice is automation level. Manual entry builds discipline but demands persistence; bank sync reduces friction but hands over data. And the common failure pattern is real: app installed, transactions go uncategorized by week three, app deleted. Budgeting is a review habit, not a software purchase.
Red flag: An app still installed with three weeks of uncategorized transactions isn’t budgeting — it’s a habit that already lapsed.
Budgeting and saving techniques the apps execute
The 50/30/20 rule divides each paycheck: 50% to needs, 30% to wants, and 20% to savings and debt repayment. It’s a heuristic, not gospel, and it structures exactly the monthly cash-flow tracking habit the apps above fill. NerdWallet’s step-by-step guide builds around it: figure out where you are, name your goals, monitor monthly cash flow, grow emergency savings, work on credit, kill high-interest debt, then revisit after big life events. It’s a loop, not a program.
The emergency fund is a progression ladder, game-style: first save $500, then level up to $1,000, then to one month’s basic living expenses. Three rungs, and the early ones come fast.
And there’s evidence writing it down works. In Charles Schwab’s 2024 Modern Wealth Survey, people with written financial plans reported feeling more in control of their money.
Debt Payoff Planner, avalanche, and snowball
The avalanche method saves the most interest mathematically, because you attack the highest rate first. The snowball method wins on motivation, because you clear the smallest balances first and feel the progress. Neither is objectively superior; pick by your own psychology and commit, because switching methods mid-stream resets momentum more than either method’s math justifies.
Debt Payoff Planner is free and makes this concrete: you enter balances, interest rates, and minimums, choose avalanche, snowball, or a custom order, and get a visual plan with your timeline and total interest paid.
Revolving debt repayment can total two to three times what was borrowed. Debt consolidation and management plans roll revolving debts into single lower-interest payments; at the same terms, a $400,000 consolidation works out to a $2,138 monthly payment. The planner’s real value is showing you a committed path instead of a guessing game.
Time value of money: the math under every planning tool
Here’s the reveal: a plain financial calculator is the engine under every planning app. Travis Sickle of Sickle Hunter Financial Advisors demonstrates this with 10Bii Calc HD, a roughly $2-3 mobile app that reportedly handles mortgage, refinance, consolidation, college, and retirement questions as well as a physical financial calculator, the same tool-first mindset behind today’s finance jobs without a degree. Less than lunch.
Watch what the math does. A $350,000 mortgage at 6% over 30 years runs $2,088 per month. Add $500 per month and payoff drops from 360 months to 224, saving over $170,000 in total paid ($579,000 versus $751,000). Or refinance to 5% and the base payment falls to $1,871.
These are illustrative numbers at the stated assumptions. Rates vary and nothing here guarantees you’ll replicate them. But the technique underneath, time value of money, is what every compound interest slider and debt payoff chart is actually computing.
Retirement planning tools for every career stage
Free retirement planning tools for individuals include Investor.gov’s Retirement Ballpark E$timate, the Social Security Retirement Estimator, the SEC’s required minimum distribution (RMD) calculator, Empower’s free net worth dashboard, and Monte Carlo simulation from Portfolio Visualizer, free to run for geeks who want to invest without paying a dime.
The most useful free framework, though, is the SEC Retirement Toolkit, which maps retirement to career stages instead of recycling generic advice: your first job, switching jobs, employer-sponsored and federal plans, managing lifetime income, senior specialist designations, and avoiding retirement fraud. It pairs well with a comprehensive financial review, and it’s a useful PDF.
If you’re at the employer-plan stage, the 401(k) match is the closest thing to free money in finance. Core planning guidance calls it exactly that, and it earns the phrase. That’s why the contribution limits matter:
| Limit (2026) | Amount |
|---|---|
| 401(k) employee contribution | $24,500 |
| Catch-up, age 50+ | +$8,000 |
| Enhanced catch-up, ages 60-63 | $11,250 |
| IRA | $7,500 ($8,600 if 50+) |
The $11,250 enhanced catch-up for ages 60 through 63 comes from the Secure 2.0 Act, which is why that narrow age window gets a bigger number than the standard catch-up. One caveat, stated once: these are forward-dated figures, so verify them against final IRS announcements before you file.
Later, the RMD calculator earns its keep. The IRS requires withdrawals from certain retirement accounts starting at specified ages, and the calculator automates those age-based rules so you don’t miss one. And for the childhood stage, the SEC’s Retirement Toolkit points to Trump Accounts, pitched as “Jumpstart Your Child’s Financial Future” with enrollment information.
Investment analysis tools: fee awareness and free analytics
The capability assumption most people get wrong: Monte Carlo simulation, portfolio backtesting, and fund fee comparison are all free. The SEC’s Fund Analyzer shows fee and expense impact over time, meaning what you’ll actually pay rather than the headline expense ratio. Portfolio Visualizer’s free tier includes Monte Carlo simulation, optimization, backtesting, and tactical allocation models, which is a surprising amount of modeling for zero dollars. (Monte Carlo, in one beat: it runs thousands of random market scenarios to show a range of possible outcomes.
It’s cool, but it doesn’t predict the future.) Empower is the home-lab dashboard: free, links your investment, retirement, and other accounts, and puts budgets, expense tracking, net worth, and goal progress on one screen. EDGAR covers the filings research, for a wider look at what these tools can and can’t do, this financial APIs research reality check is worth a read, and the Investment Professional Background Check covers vetting the humans.
Investor.gov spotlights, quizzes, and audience resources
There’s more on Investor.gov than calculators. Spotlights cover Common Scams and Crypto Assets, plus HoweyTrade, a fictional scam platform the SEC built to teach the warning tells of fraud. The regulators invented a pretend fraud scheme to sharpen your instincts, which is kind of great. There are investing quizzes if you want to test yourself, and World Investor Week 2026, a global investor education and protection campaign, runs under the theme “Invest in Your Future. Protect It Today.”
Audience lanes exist for students, military members, veterans, older investors, teachers, youth, and entrepreneurs. The SEC Office of Investor Education and Assistance is the human-help arm: real people handle investor questions and complaints. And MyMoney.gov, the federal financial-literacy site, sits in the footer as a worthy companion.
When free tools stop: the fiduciary advisor boundary
Free tools stop being adequate when your situation involves Roth conversions, tax-loss harvesting, or withdrawal sequencing, or when you’re facing a job change, an inheritance, a divorce, or business ownership. At that point a calculator output isn’t approximately right for you; it’s systematically wrong, because free tools run on standardized assumptions (fixed returns, fixed inflation, standard life expectancy) and evaluate one scenario at a time. A fiduciary advisor works from your actual data and can model your actual life.
What advisors add beyond the math:
- Personalized strategy: Roth conversions, tax-loss harvesting, and withdrawal sequencing are moves calculators can’t design.
- Orchestration: modeling complex events like an inheritance or business sale, and coordinating attorneys and tax professionals.
- Behavioral coaching: panic-selling in downturns is where portfolio performance actually dies, and a human guardrail that keeps you on plan is worth real money.
- Whole-picture review: capital needs, financing sources, and policies for cash, lending, and borrowing, revised as things change.
Costs run on flat fees, hourly rates, or a percentage of assets, and some advisors impose $250,000+ account minimums. Which leads to the honest middle paths. Robo-advisors are a narrower, lower-cost option for straightforward portfolios. And for simple finances, free tools plus occasional fiduciary consultations is often the cost-effective setup, because advisor value scales with complexity. A common inflection point is a first windfall or business launch, not a first budget. Neither “cancel your advisor” nor “you must hire one” is the move; the complexity decides.
Cost check: Advisor value scales with complexity — a simple budget rarely needs one, but a windfall or business sale changes the math.
The professional playbook: The Tools & Techniques of Financial Planning
The 14th edition of The Tools & Techniques of Financial Planning is practitioner material, built for CFP-track professionals, and you don’t need it as an individual. But it’s interesting anyway. It’s part of the Leimberg Library, a nine-book Tools & Techniques series created by Stephan R. Leimberg, who also built practitioner software like NumberCruncher and runs LISI, a newsletter and database service used daily by thousands of professionals across estate, financial, benefit, and retirement planning. Coverage spans budgeting, credit and debt, education funding, retirement, tax, risk and insurance, and estate planning, with checklists, case studies, real citations, and CFP ethics standards. The nerd-snipe detail: a newly revised Time Value of Money chapter with step-by-step calculator instructions.
The credentials hold up. Carolynn B. Tomin spent more than two decades directing Boston University’s financial planning programs, and in 2012 led the CFP Board’s Council on Education. William B. Reeve, CFP, CFA, and Enrolled Agent, taught at BU for 15+ years and has been a Northeastern adjunct since 1996.
The honest close: you don’t need this book, and you don’t need a pirated PDF of it. The free ecosystem covers consumer needs right up until the advisor-boundary triggers above.
Planning moves no app performs
Four moves no app executes for you: tune your W-4, because a hefty refund can signal you lent the government money interest-free all year; get term life insurance, where 10 to 30 year terms fit most needs; put estate documents in place so your stuff goes where you intend; and, for heavy revolving debt, a debt management plan can combine balances at lower interest. Pick one, do it, done.
Building your tool stack, and securing it
Reputable free budgeting and investing apps are reasonable to link to your bank, when you do the basic hygiene. Match tool to job: Goodbudget or MoLo for daily spending, Empower and Portfolio Visualizer for net worth and analytics, Debt Payoff Planner for debt. Combos work; a spreadsheet for goals plus an app for daily spending gives a fuller picture than either alone. And the natural adoption sequence across a financial life runs spreadsheet, then app, then advisor as complexity grows.
On security, it’s calm and practical: reputable tools use encryption and safeguards, especially for linked accounts. Read the privacy policy to see how data is stored and whether it’s shared with third parties. Pick reputable developers. Enable multi-factor authentication and strong passwords. You’re linking your bank; do the thing.
One gap worth naming: free, personalized advice for low incomes mostly looks like the human channel above, the SEC Office of Investor Education and Assistance for questions, plus nonprofit counseling resources like ACCC, rather than a free substitute for an advisor.
Name the technique, pick the smallest free tool that runs it, and know the specific triggers that upgrade you to an advisor. And remember the Schwab finding: a written plan is what correlates with feeling in control. The plan is the asset; the app is just where it lives.
Frequently Asked Questions
How does the 50/30/20 budget rule work for tracking monthly cash flow?
The 50/30/20 rule divides each paycheck into 50% for needs, 30% for wants, and 20% for savings and debt repayment. It structures exactly the monthly cash-flow tracking habit that budgeting apps fill: categorize your spending, compare it against the three buckets, and review regularly. It’s a heuristic, not gospel, but it gives your monthly review a concrete structure.
Debt snowball vs avalanche method: which payoff strategy saves more money?
The avalanche method saves the most interest mathematically because you attack the highest interest rate first, while the snowball method wins on motivation by clearing the smallest balances first. Neither is objectively superior — pick based on your own psychology and commit, because switching methods mid-stream resets momentum more than either method’s math justifies. Free tools like Debt Payoff Planner let you model both before choosing.
free financial advisor for low income: what options actually exist?
Free personalized guidance for lower incomes mostly runs through the human channel: the SEC’s Office of Investor Education and Assistance handles investor questions and complaints with real people, and nonprofit counseling resources like American Consumer Credit Counseling (ACCC) offer free worksheets and credit counseling. There’s no true free substitute for a fiduciary advisor, but these resources cover a lot of ground at zero cost.
Is Investor.gov really free, and what does it include?
Yes — Investor.gov is the SEC’s free toolkit with no signup and no cost, run by the regulators themselves. It bundles five tools (Fund Analyzer, Retirement Ballpark E$timate, Social Security Retirement Estimator, EDGAR, and an Investment Professional Background Check) plus four calculators covering compound interest, savings goals, required minimum distributions, and college savings.
How much does an extra $500 per month actually save on a mortgage?
On a $350,000 mortgage at 6% over 30 years, adding $500 per month cuts the payoff from 360 months down to 224 and saves over $170,000 in total paid ($579,000 versus $751,000). These are illustrative numbers at the stated assumptions — rates vary — but they show why time value of money is the math underneath every planning tool.
